A pre approved credit card offer is not a guarantee. What it means, why final approval can still fail, and what RBI rules protect you.
Quick Verdict
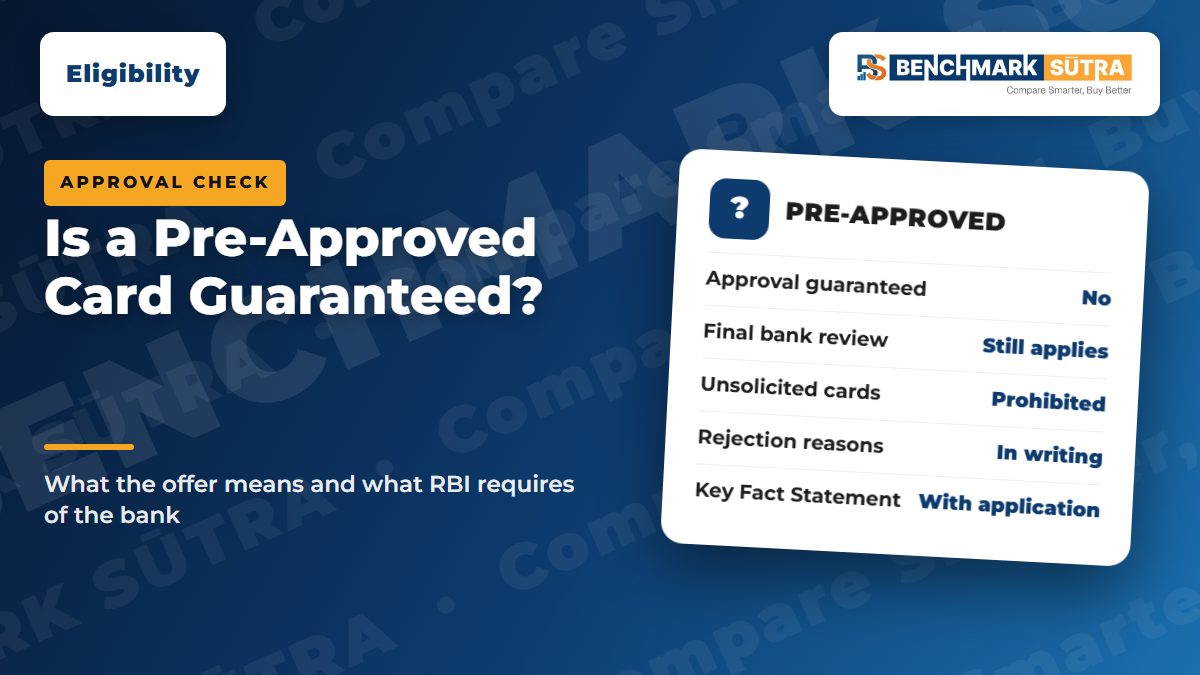
No. A pre-approved credit card offer does not guarantee approval. It is the bank telling you that you look like a good fit on the data it holds, and the application still goes through the bank's final checks. HDFC Bank's own pre-approved flow shows this: it contains a screen that says you are not eligible for the card at the moment, and it carries the line "Subject to application approval".
Our view: treat apre approved credit cardmessage as a shortcut, not a promise. The useful part is that your details are often pre-filled, so you skip some paperwork. The risky part is the wording. "Congratulations, you are pre-approved" sounds like a limit and a card are reserved for you, and nothing in the RBI directions we read says that. What RBI does require is that you get a one-page Key Fact Statement with the application, receive the Most Important Terms and Conditions (MITC), and give explicit consent. This article is researched from those documents. We have not tested it by applying to every bank.
For a CA, lawyer or doctor with irregular practice income, the offer is worth a look only after you check what the bank is actually offering: which card, which fee, and which conditions.
Question | Short answer |
|---|---|
Is approval guaranteed? | No. The bank's final review still applies (HDFC's flow says "Subject to application approval") |
Where do I check an offer? | On the bank's own page or app; read the consent text before you tick it |
Can the bank send me a card I never asked for? | No. RBI prohibits unsolicited cards and upgrades |
If I am rejected, will I know why? | RBI requires the issuer to convey the specific reasons in writing |
Do I still get the fee and rate details? | Yes. A Key Fact Statement must come with the application and the MITC at onboarding |
Compare the card you are offered with ones you would pick yourself usinghow to compare credit cards in India.
What Does a Pre-Approved Credit Card Offer Actually Mean?
"Pre-approved" is a banking and marketing term, not a legal promise. Banks use what they already know about you, such as your account history with them, to decide whom to show an offer to. The offer then goes into an application flow, and the flow is where the decision is made.
HDFC Bank's pre-approved page is a good example. Its flow tells an eligible customer which card they are eligible for, asks them to validate ID and address documents, shows the card's joining and renewal fee, and asks them to confirm they have read the card price and features. The same flow has messages for the other outcome. One says you are not eligible for the card at the moment and suggests other cards. Another says you are not eligible for a Lifetime Free or First Year Free card based on your latest employment detail. At the end, the confirmation says delivery is "subject to application approval" and that you will be notified by email and SMS once approved.
Read together, a pre-approved offer is a strong signal that the bank is willing to consider you, with fewer documents. It is not a signed commitment. We have read only HDFC's page in detail. Other banks may word and run their flows differently, so read your own bank's page and its terms.
Pre-Approved vs Regular Application: What Changes?
Point | Pre-approved offer | Regular application |
|---|---|---|
Who starts it | The bank shows you an offer | You choose the card and apply |
Details | Often pre-filled; you validate them (HDFC flow) | You enter income, employment and address |
Documents | ID and address validation shown in HDFC's flow | Bank may ask for income proof, as per its policy |
Fee and benefits | Shown on the offer screen; you confirm you have read them | Shown on the product page and the Key Fact Statement |
Final approval | Still subject to the bank's approval | Subject to the bank's approval |
Rejection | Possible; RBI requires written reasons | Possible; RBI requires written reasons |
The "Documents" row is the real saving. What a pre-approved offer saves is your time. It does not remove the bank's checking.
What Do RBI Rules Say About Offers and Consent?
RBI's RBI, Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025 (updated as on 1 October 2026) gives you rights that apply whether the offer is pre-approved or not. In the version we read:
The issue of unsolicited cards and upgrades is strictly prohibited. A card-issuer shall not dispatch a card to a customer unsolicited.
Consent must be explicit and not implied. It is taken in writing, or through digital modes with multi-factor authentication.
A one-page Key Fact Statement, including the rate of interest and charges, must come with the application.
The MITC must be given at onboarding, and again when a condition is modified.
If an application is rejected, the issuer must convey in writing the specific reasons.
Card-issuers shall not unilaterally upgrade cards or enhance credit limits. Reductions in limits must be intimated to you.
The issuer's representatives may contact you only between 10:00 and 19:00, and telemarketers must follow TRAI and NCPR rules.
Credit information on a new card account must not be reported before the card is activated.
The last point matters for pre-approved offers. Per the Directions, a new card account is not reported to the credit bureaus before activation. Do not assume more than that, and check your bank's terms.
Why Would a Pre-Approved Offer Still Fail?
Because "pre-approved" rests on the bank's earlier view of you, and the final step looks at what you declare now. HDFC's own flow gives two examples: employment details that do not match a card's eligibility, and a card category that does not fit what you declared. In both cases the flow does not simply issue the card. It declines it or points you to a different one.
For professionals, the mismatch is often about how income is described. A partner in a firm, a consultant and a salaried doctor are three different profiles. If you declare income in a way that differs from what the offer assumed, the card on offer can change. Declare your income as it truly is. A wrong declaration risks rejection, and every application can leave a trace on your credit report.
If you are rejected, ask for the written reason RBI requires, and read5 common reasons your credit card was rejectedbefore you reapply. If your income is uneven,how to get a credit card as a freelancerandthese approval tipscover what to prepare.
Checklist: Before You Accept a Pre-Approved Offer
Open the offer only from the bank's own app, net banking or website. Do not click links in messages you cannot verify.
Note the card name. Is it the card you want, or only the card the bank wants to sell?
Read the joining and annual fee and any waiver condition on the offer screen.
Read the Key Fact Statement and the MITC before consenting. Look at the interest rate (APR), the late payment charge and the forex markup.
Check how the bank describes your income and employment. Correct it if it is wrong.
If you already carry other cards, use thecredit utilisation calculatorto see how a new limit changes your overall usage.
Never share an OTP with a caller. As per RBI, issuers' representatives may contact you only between 10:00 and 19:00.
Save the confirmation and the SMS or email you get once the bank decides.
Common Mistakes to Avoid
Treating "pre-approved" as "guaranteed".Do not plan a purchase around a card or limit you have not received.
Accepting the first card on offer.It may carry a fee that another card from the same bank would avoid. Ourcredit card fee guidelists every charge to look for.
Giving wrong income details to fit the offer.It risks rejection and can cause trouble later.
Ignoring the consent text.You are agreeing to terms, calls and messages.
Applying to several banks at once because each says you are pre-approved.Each application can leave a trace on your credit report.
Trusting unknown callers.RBI limits when issuers' representatives may call. If a call falls outside those hours or asks for an OTP, hang up and use the number printed on your bank's site.
Related on benchmarksutra
FAQs
Does a pre-approved credit card offer guarantee approval?
No. The bank's final approval still applies. HDFC Bank's pre-approved flow itself shows an ineligibility message and a note that the card is subject to application approval.
What is a pre-approved credit card?
It is a card the bank offers you based on data it already holds, often with details pre-filled. You still confirm the card terms and complete the application.
Can a bank reject me after a pre-approved offer?
Yes. If it does, RBI requires the issuer to convey the specific reasons in writing.
Can a bank send me a credit card I did not ask for?
No. RBI's card Directions prohibit unsolicited cards and upgrades, and require explicit consent.
Will a pre-approved offer affect my credit score?
We could not confirm a bank-specific statement on this from official pages. Read the consent text and ask the bank whether a credit enquiry will be made before you accept.
Do I get a Key Fact Statement for a pre-approved card?
RBI requires a one-page Key Fact Statement along with the credit card application, with the rate of interest and charges. HDFC's flow also lists it in the consent text.
Is a pre-approved offer better for self-employed professionals?
It can save documents, but the final card depends on your declared income and employment. Declare it accurately.
Official Sources and Editorial Note
This article is written from official sources and does not rely on third-party wording.