A credit card against FD needs no income proof at some banks. See limits, minimum FDs, age caps and costs for IDFC FIRST, Kotak and ICICI, for retirees.
Quick Verdict
Acredit card against FDis a card whose limit is backed by a fixed deposit you keep with the bank. The bank places a lien on the deposit, issues the card without asking for income proof or a credit history, and sets your limit as a share of the FD. Banks we checked cap it at up to 90% of the deposit (ICICI, Kotak) or set it at 100% or more (IDFC FIRST).
For retirees, it is often the easiest way to get a card when salary slips are missing and pension income is hard to document. The price is that your money stays locked while the card is open, so treat it as a tool for paying bills and rebuilding a credit record, not for rewards.
Question | Short answer |
|---|---|
What backs the limit? | A fixed deposit with the same bank, held under lien |
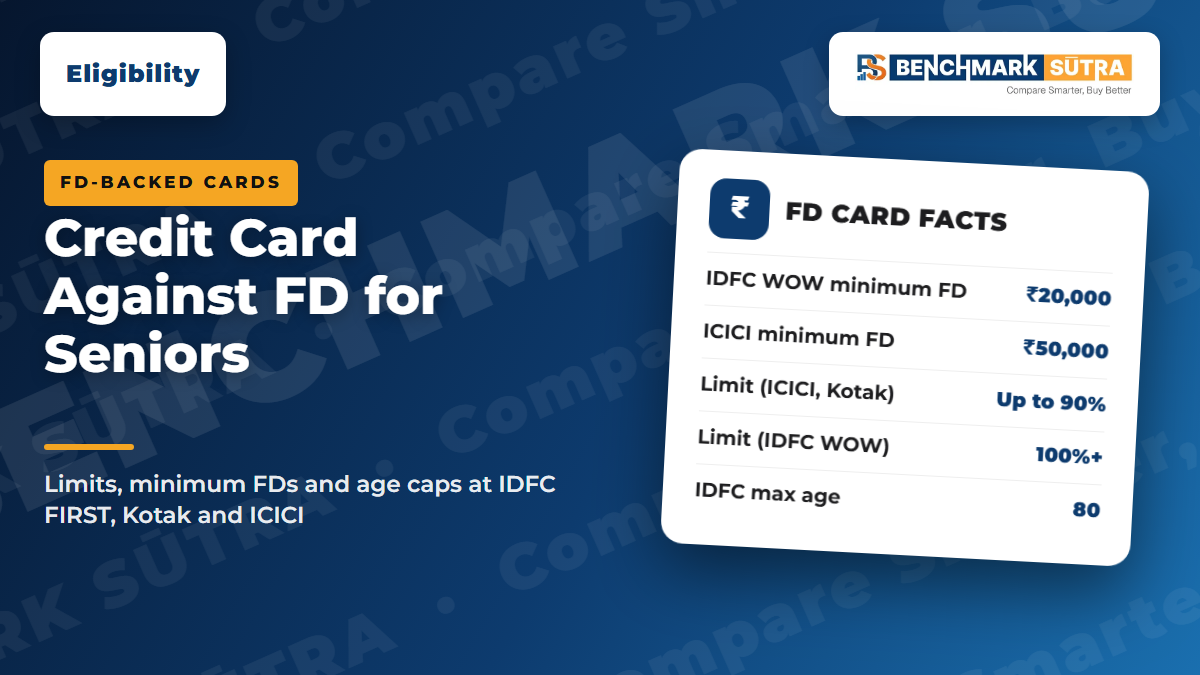
Limit size (as of November 2026) | Up to 90% of the FD (ICICI, Kotak); at least 100% (IDFC FIRST WOW) |
Minimum FD | ₹20,000 (IDFC FIRST WOW); ₹50,000 (ICICI Instant Platinum); Kotak does not state it on the pages we read |
Income proof needed? | IDFC FIRST says no income proof or credit history |
Maximum age | 80 (IDFC FIRST WOW); 75 (Kotak 811 Dream Different) |
Main risk | Unpaid dues can be recovered from the locked FD, and interest on unpaid balances is high |
Your cohort here is the retiree or senior citizen who holds FDs but has no regular payslip. The sections below use that situation.
How Does a Credit Card Against a Fixed Deposit Work?
You apply at the bank that holds your FD, or open an FD while applying. The bank marks a lien on the deposit. You cannot break or withdraw that FD while the lien is in place. The card works like a normal credit card for shopping and bills, with a monthly statement and a due date.
Limit:a percentage of the FD. ICICI's page says up to 90%. Kotak says up to 90% of the lien amount. IDFC FIRST says at least 100% of the FD for its WOW card.
Your FD keeps earning:IDFC FIRST states the FD continues to earn interest. Check this with your own bank before you apply.
Approval:because the bank already holds your money, it does not rely on salary or past borrowing. IDFC FIRST says no income proof or credit history is needed.
If you do not pay:the lien lets the bank recover dues from the deposit. Read the lien clause in the bank's terms before you sign.
Under RBI's Credit Cards and Debit Cards Directions, 2025, a card issuer must give you at least one fortnight after the statement to pay before it charges interest, and it must show annualised interest rates with equal prominence to the fee. These rules apply to FD-backed cards too. The Direction we read has no separate provision on cards against deposits, so the bank's own terms govern the lien.
Which FD-Backed Cards Can Seniors Compare?
We checked three FD-backed cards from official pages. All three have no annual fee on the pages we read. The table also shows the Benchmarksutra Score for each (method:how we score credit cards).
Card | Minimum FD | Limit | Age limit | Rewards | Benchmarksutra Score |
|---|---|---|---|---|---|
IDFC FIRST WOW! | ₹20,000 | At least 100% of FD | 18–80 | 4 reward points per ₹200 (0.5%); ₹99 + GST per redemption | 73/100, B Tier |
Kotak 811 Dream Different | Not stated on pages read | Up to 90% of FD lien | 18–75 | 2 points per ₹100 online, 1 per ₹100 elsewhere | 60/100, C Tier |
ICICI Instant Platinum (against FD) | ₹50,000, 180-day minimum tenure | Up to 90% of FD | Not stated | 2 points per ₹100 per page (page has dated notes) | 57/100, Avoid unless niche use case |
IDFC FIRST WOW! has the widest age band and the lowest FD entry point. We reviewed it separately inthe IDFC FIRST WOW credit card math, so this article does not repeat that working.
What Does a ₹2 Lakh FD Get You?
Here is an illustration using a ₹2,00,000 FD. These are limit ceilings from the pages above. The bank sets your actual limit.
Bank | Limit rule | Limit on a ₹2,00,000 FD |
|---|---|---|
ICICI Instant Platinum | Up to 90% | Up to ₹1,80,000 |
Kotak 811 Dream Different | Up to 90% of lien amount | Up to ₹1,80,000 |
IDFC FIRST WOW! | At least 100% of FD | At least ₹2,00,000 |
A high limit is not a reason to spend more. Your FD is the safety net, so use the card for fixed monthly bills and pay the full amount each month. Ourcredit utilisation calculatorshows how much of the limit you are using.
Why Interest Matters More Than Rewards
Kotak's FAQ shows a 3.50% monthly interest illustration and a 4% foreign-currency markup. That page may predate the current schedule of charges, so confirm both figures before you apply. Even so, it shows the point: revolving a balance on an FD-backed card is expensive.
Unpaid balance | Interest at 3.50% a month (Kotak FAQ illustration) |
|---|---|
₹5,000 | ₹175 |
₹10,000 | ₹350 |
₹25,000 | ₹875 |
Rewards at 0.5% on ₹10,000 of spend earn roughly ₹50 in points. One month of interest on the same unpaid ₹10,000 is ₹350. Pay the total amount due, not the minimum. Our guide ontotal amount due vs minimum amount dueexplains the difference.
Who Should Take a Card Against FD?
Retirees without payslips:pension credits and interest income are real income, but many card forms still ask for salary slips. An FD-backed card avoids that step.
Seniors with no credit history:if you never borrowed, a secured card gives you a record. See7 hacks to boost your approval chances with low income.
People rejected before:common reasons for rejectionare mostly about income or history, which an FD sidesteps.
Those who can spare the FD:only lock money you will not need for the card's life. Keep your emergency and medical funds outside the lien.
If you want a spouse or family member to use the card too, ask the bank about add-on cards. Our explainer onadd-on credit cardscovers how they work in general. We could not confirm from the pages above whether these FD-backed cards allow add-ons.
Checklist
Confirm the minimum FD, the tenure rule and the maximum age on the bank's page today.
Ask whether the FD earns interest while under lien and what happens at maturity.
Read the lien clause: when can the bank recover dues from the deposit?
Find the interest rate per month and per year (APR), plus forex markup and any redemption fee.
Set up auto-debit for the total amount due so you never miss a date.
Use the card for regular bills for six to twelve months, then check whether the bank offers an unsecured upgrade.
Keep your emergency money outside the FD you pledge.
Common Mistakes to Avoid
Pledging your only FD.You cannot touch it while the lien stands.
Paying only the minimum due.Interest then runs on the whole balance.
Chasing rewards.At 0.5% or so, rewards are small next to one month of interest.
Assuming the page is current.ICICI's product page carries older notes. Check the bank's latest schedule of charges.
Applying at several banks.Each application can be a hard enquiry. Seehard vs soft enquiry.
Related on benchmarksutra
FAQs
How does a credit card against a fixed deposit work?
The bank places a lien on your FD and issues a card with a limit set as a share of that deposit. You use and repay it like any credit card, and the FD stays locked until the card is closed or the lien is released.
Can a senior citizen get a credit card against FD without income proof?
IDFC FIRST says its WOW! card needs no income proof or credit history, with an age band of 18 to 80 and an FD of ₹20,000 or more. Other banks may ask for documents, so check their pages.
How much credit limit do I get on an FD-backed card?
ICICI says up to 90% of the FD and Kotak says up to 90% of the lien amount. IDFC FIRST says at least 100% of the FD for its WOW! card.
Does my FD still earn interest?
IDFC FIRST states that the FD keeps earning interest. For any other bank, confirm this in the terms before you pledge the deposit.
What happens if I do not pay the bill?
The bank can recover unpaid dues from the FD under the lien, and interest is charged on the unpaid balance. Read the lien and interest terms before applying.
Will an FD-backed card help build my credit record?
It can, if you spend modestly and pay the full amount on time. Ask the bank whether it reports card performance to credit bureaus.
Is an FD-backed card a good rewards card?
Not usually. IDFC FIRST WOW! earns about 0.5% and charges ₹99 + GST per redemption, and point values are not stated for the others.
Official Sources and Editorial Note
This article is written from official sources and does not rely on third-party wording.