
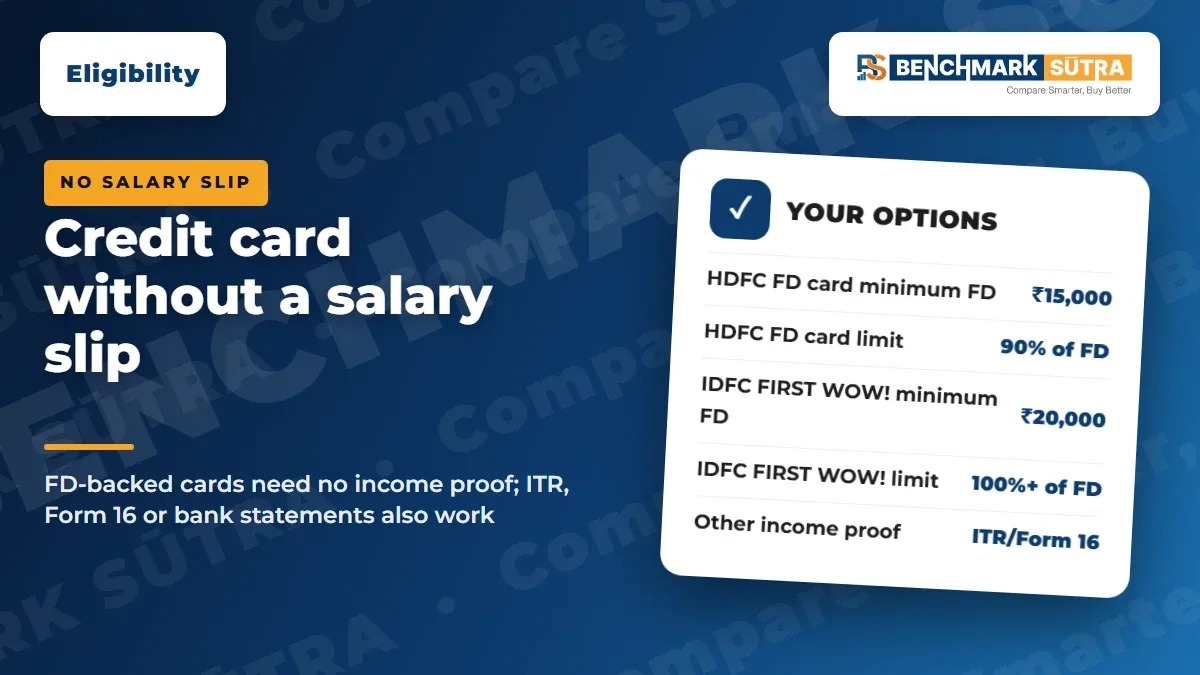
No payslip? You can still get a credit card in India: an FD-backed card needs no income proof, or use ITR, Form 16 or bank statements. Options, limits and pitfalls.
Quick Verdict
Yes, you can get a credit card without a salary slip in India. The easiest route is a credit card against a fixed deposit, which banks issue without any income proof. The other route is to prove income another way, such as an Income Tax Return (ITR), Form 16 or bank statements.
What you cannot skip is some basis for credit. RBI's card rules require banks to assess your "independent financial means" before issuing a card. So a bank needs either proof that you earn, or a deposit that secures the limit.
Your situation | Best route without a salary slip |
|---|---|
First job, no payslip yet | Card against an FD, or wait for salary credits and use bank statements |
Student or homemaker with savings | Card against an FD |
Freelancer or self-employed | ITR as income proof, or a card against an FD |
Salaried, but payslips are informal | Form 16 or bank statements showing salary credits |
Low or no credit score | Card against an FD to build a repayment record |
Why Banks Ask for a Salary Slip
A credit card is unsecured credit. RBI's 2025 card directions tell banks to "independently assess the credit risk" while issuing cards, "taking into account independent financial means of applicants". Banks must also consider the limits you already have on other cards.
A salary slip is just the most common proof of means. It is not the only one. HDFC Bank's Freedom card page, for example, lists four kinds of income proof:
salary slips (for salaried people)
Income Tax Returns (ITR)
Form 16
bank statements
The same page sets income thresholds: a net monthly income above ₹12,000 for salaried applicants, or an ITR above ₹6 lakh a year for the self-employed. Other cards and banks set their own limits, so check the card's own page.
Option 1: A Credit Card Against a Fixed Deposit
This is the surest way to get a credit card without a salary slip. You open a fixed deposit (FD) with the bank, and the bank issues a card with a limit linked to that FD. Because the deposit secures the limit, the bank does not need your income proof.
Here is how two banks describe their FD-backed cards, as of November 2026:
Feature | HDFC Bank Credit Card against FD | IDFC FIRST WOW! Credit Card |
|---|---|---|
Income proof | Not required | Not required |
Credit history | Suits no or low credit history | Not required |
Minimum FD | ₹15,000 (tenure of at least 1 year) | ₹20,000 |
Credit limit | 90% of the FD amount | At least 100% of the FD amount |
Age | 18 to 75 years | 18 to 80 years |
FD keeps earning interest? | Yes | Yes |
Annual fee | Not stated on the FD card page; check the card offered | Lifetime free (the UPI-enabled digital card costs ₹199 + GST a year) |
These are examples of how FD-backed cards work, not a ranking. Other banks offer similar cards with different minimums and fees.
What to know before you pick an FD-backed card
Your FD is locked as security. HDFC says that if you do not repay, it deducts the dues from the pledged FD.
Not every FD qualifies. HDFC excludes tax-saver, NRI, minor, sweep-in and non-withdrawable FDs, and FDs already under lien. It also needs an updated, operative PAN.
Interest still applies. HDFC says FD-backed cards carry the same revolving interest rate as the matching card variant. SBI Card's MITC lists 2.75% a month (33% a year) for its secured cards. Pay in full to avoid it.
Activate within 30 days. RBI rules require banks to close a card that is not activated within 30 days if you do not give consent. HDFC's FD card page gives the same warning.
Option 2: Use Another Income Proof
If you have income but no formal payslip, show it another way.
Document | Who it suits | Tip |
|---|---|---|
Income Tax Return (ITR) | Freelancers, consultants, business owners, first jobbers who have filed | File on time every year; banks often look at the latest ITR |
Form 16 | Salaried people whose employer deducts TDS | Ask your employer for it after the financial year closes |
Bank statements | Anyone with regular credits into one account | Let your salary or client payments land in one account for a few months |
For freelancers, our guide on How to Get a Credit Card as a Freelancer covers this in detail.
Option 3: Apply Where You Already Bank
Your own bank already has your KYC and sees your account flows. HDFC Bank's FAQ says existing customers do not need identity or address proof again, though income proof is still needed for a standard card. HDFC also says you cannot hold two HDFC Bank credit cards at once.
Applying with your salary or savings bank is often simpler than starting fresh elsewhere. Just do not assume it skips the income check.
Option 4: An Add-on Card
A parent or spouse with a card can request an add-on card for you. Under RBI rules, the add-on is issued within the primary cardholder's limit, and the liability for dues rests with the primary cardholder alone.
That makes it a way to use a card without income proof. It is not your own credit line, so it does not replace getting a card in your own name.
Can I Get a Credit Card Without a Salary Slip as a First Jobber?
Yes. A typical path looks like this:
Month 1: open an FD-backed card with a small FD you can spare. Use it for a few planned spends.
Every month: pay the full bill by the due date. This builds your repayment record with the credit bureaus.
After a few salary credits: your bank statements now show regular income.
After your first ITR or Form 16: apply for an unsecured card using that proof.
Before you apply, read Credit Card 101: A Beginner's Guide.
What If Your Application Is Rejected?
RBI rules require the bank to tell you the specific reasons for rejection in writing. Use them. If income proof was the issue, switch to an FD-backed card or wait for an ITR.
Do not apply to several banks in a row. Our guides on 5 Common Reasons Your Credit Card Was Rejected and 7 Hacks to Boost Approval Chances With Low Income explain what to fix first.
Checklist
Do you have an ITR, Form 16 or a few months of bank statements with regular credits?
If not, do you have ₹15,000 to ₹20,000 you can lock in an FD for at least a year?
Is your PAN updated and operative?
Is the FD a type the bank accepts (not tax-saver, sweep-in or already under lien)?
Have you read the Key Fact Statement for the fee and interest rate?
Will you activate the card within 30 days?
Have you set autopay for the full amount due?
Common Mistakes to Avoid
Mistake 1: Paying an agent to "arrange" approval
RBI rules say only the bank can decide to issue a card. Agents can only solicit and service. Apply through the bank's official site or branch.
Mistake 2: Submitting edited or borrowed documents
Banks verify income proof. A false document can lead to rejection and other consequences. Use a genuine ITR, Form 16, statement or an FD instead.
Mistake 3: Using the full FD-backed limit
A high balance, even if repaid, looks like heavy use of credit. Keep spends modest and repay in full.
Mistake 4: Breaking the FD early
The FD secures the card. Plan with money you will not need for at least a year.
Mistake 5: Treating an add-on card as your own credit
The primary cardholder is liable for dues. Get your own card when you can.
FAQs
Can I get a credit card without a salary slip in India?
Yes. You can get a card against a fixed deposit without income proof, or use an ITR, Form 16 or bank statements as income proof instead.
Which credit card needs no income proof?
Cards issued against a fixed deposit. HDFC Bank and IDFC FIRST Bank, for example, both say their FD-backed cards need no income proof.
How much FD do I need for a credit card?
It depends on the bank. HDFC Bank's minimum is ₹15,000 and IDFC FIRST's FIRST WOW! card needs ₹20,000, as of November 2026.
Can I use ITR instead of a salary slip?
Yes. Banks such as HDFC Bank list ITR as accepted income proof, alongside Form 16 and bank statements.
Does an FD-backed credit card build my credit score?
It gives you a repayment record with the credit bureaus. Paying the full bill on time, every month, is what helps your score.
Will I lose my FD if I miss a payment?
The bank can recover unpaid dues from the pledged FD. HDFC Bank's FAQ says it deducts the dues from the FD if you do not repay.
Can a student get a credit card without income?
Yes, through an FD-backed card. IDFC FIRST's WOW! card, for example, accepts applicants from age 18 with no income proof or credit history.
Official Sources and Editorial Note
Data checked as of: 4 November 2026
RBI (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025, updated as on 1 October 2026
https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=13155
HDFC Bank Credit Card against Fixed Deposit page
https://www.hdfc.bank.in/credit-cards/credit-card-against-fd
HDFC Bank Freedom Credit Card page (eligibility and income documents)
https://www.hdfc.bank.in/credit-cards/freedom-credit-card
HDFC Bank Credit Cards page (FAQs on documents)
https://www.hdfc.bank.in/credit-cards
HDFC Bank Credit Card MITC, version 4.18, October 2026 (FD-backed card interest)
HDFC Bank MITC (PDF)
IDFC FIRST Bank FIRST WOW! Credit Card page
https://www.idfcfirst.bank.in/credit-card/wow
SBI Card Most Important Terms and Conditions (secured card interest rate)
SBI Card MITC (PDF)
Important source note:
This article is written from official sources and does not rely on third-party wording. Bank products named here are examples of how FD-backed cards work, not ranked recommendations.
Editorial note:
Eligibility, FD minimums and fees change. Check the bank's current page and Key Fact Statement before applying.

