Can you get a new credit card based on your existing one? What RBI rules, limits and consent mean, and your real options as a frequent flyer.
Quick Verdict
No, you cannot get a credit card based on your existing credit card in the sense of borrowing its limit. A bank assesses each credit card application on its own, and it counts the limits you already hold on other cards when it sets a new limit. A credit card against an existing credit card is not a product with its own category in the bank terms we reviewed.
What you can do is use your card history to help the next application: pay on time, keep your balance low, and apply to the same bank or ask for an upgrade, which the bank can only do with your consent. This guide is for frequent flyers who already hold a card and want a travel-focused one, as of November 2026.
Question | Short answer |
|---|---|
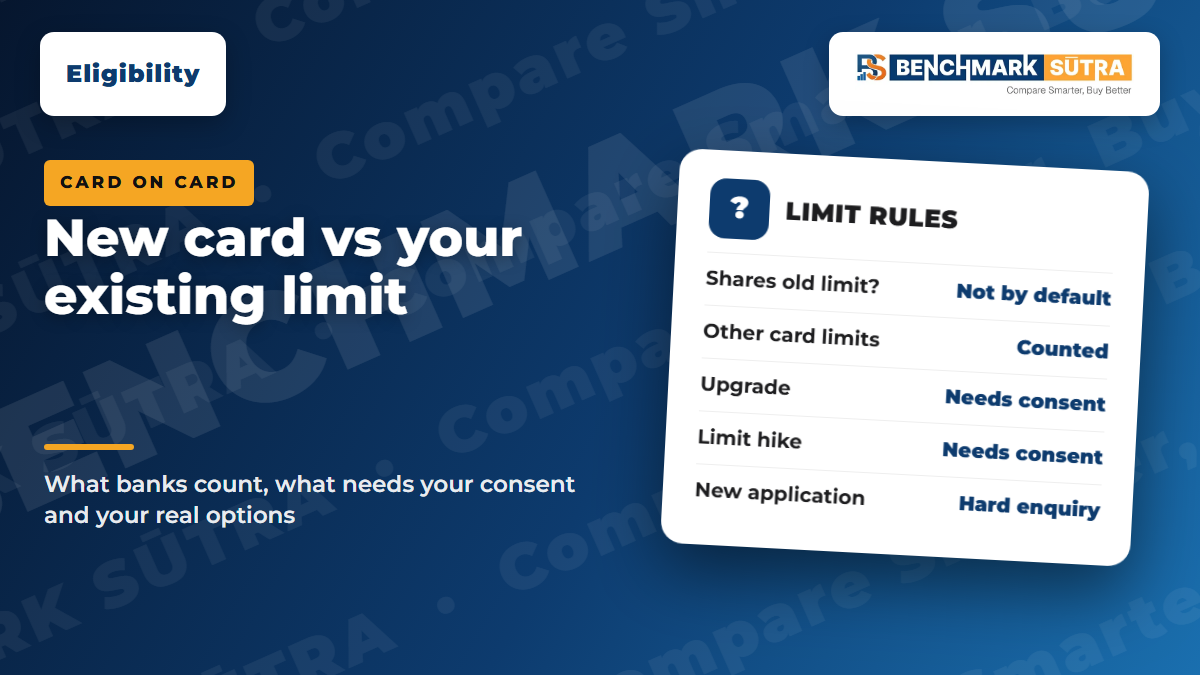
Does a new card share my old card's limit? | Not by default. A new card account gets its own assessment. |
Will the bank count my old limits? | Yes. RBI requires banks to count limits on your other cards. |
Can the bank upgrade me automatically? | No. Upgrades and limit increases need your consent. |
Can I ask for an upgrade or a higher limit? | Yes. The bank decides. |
Does a new application affect my score? | It can add a hard enquiry to your credit report. |
Before you apply, check:
your current limits and how much you use
your credit score and recent hard enquiries
whether the bank offers an upgrade path for your card
the new card's fee against the travel benefit you will really use
whether an add-on or secured card fits your goal better
What Does "Credit Card Against Existing Credit Card" Mean?
People searching for a credit card against an existing credit card usually mean one of four things.
What you mean | Is it possible? | What to do |
|---|---|---|
A new card that uses my old card's limit | Not by default | Ask the bank about a limit transfer or upgrade; it is the bank's choice |
A new card from the same bank, easier approval | Sometimes | Your repayment history with the bank is on file; approval is still not guaranteed |
Move up to a better card | Yes, with consent | Request an upgrade; the bank cannot do it without asking you |
Cash against my card limit | Different product | That is a cash advance or a loan; check the fee and interest first |
The RBI Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025 do not create a separate "card on card" category. They set rules for consent, limits and assessment that apply to every card.
How Do Banks Treat Your Existing Cards When You Apply?
Under RBI's directions for commercial banks, the bank must assess your independent financial means before it issues a card. It must also count the credit limits you already have on other cards, using either your own declaration or data from the credit bureaus. In practice, a second or third card often comes with a lower limit, because the bank looks at your total credit.
The bank can also look at how you handle the cards you hold: whether you pay in full, how much of your limit you use, and whether you missed any dues. Our guide oncredit limits explainedshows how limits are set, andCIBIL score for a credit cardcovers the score side. Each application can create a hard enquiry. Too many in a short window can lower your chances, which we explain inhard enquiry vs soft enquiry.
What a frequent flyer should know
Travel cards usually have higher fees and higher income rules than a first card. If your old card is an entry-level one, a travel card may need a higher income or a better history with the bank. Compare the benefits inbest credit cards for international travelandIndiGo vs Air India credit cardsbefore applying.
What Are Your Real Options?
1. Ask for a limit increase on the card you have
A bank can raise your limit, but not on its own. RBI bars unilateral limit increases without your explicit consent. If you want more room, ask. Seehow banks increase credit card limit. If you use more than your limit, remember theover-limit feeand that over-limit use needs your opt-in.
2. Ask for an upgrade to a better card
If the bank has a higher variant of your card, ask whether you qualify. The bank can offer; you must consent. Check the new card's fee, as upgrades can bring a higher annual fee.
3. Apply for a new card, ideally one at a time
Apply to a card you meet the eligibility for. Use the issuer's own page to check the income and city rules. If you are turned down, wait before you try again. Our guide onhow long to wait after a rejectionexplains why.
4. Use an add-on card
If your goal is another card for a family member, an add-on is linked to your account. Readadd-on credit cards explained.
5. Consider a secured card
If your limit or income is the problem, a card backed by a fixed deposit works from your deposit rather than from your card history. Seethe FD-backed card maths.
How Does the Total Limit Change With a New Card?
This example is our own illustration with round numbers. It shows how the bank may think about total credit, not what any bank will actually offer.
Item | Amount (₹) |
|---|---|
Limit on existing card | 2,00,000 |
Average monthly spend on it | 40,000 |
Utilisation of existing card | 20% |
New card limit offered (assumption) | 1,50,000 |
Total limits across both cards | 3,50,000 |
Same ₹40,000 spend across both | About 11% utilisation |
Two cards can lower your utilisation if your spend stays the same, but only if the bank approves a decent limit. Do not treat a bigger total limit as money to spend. Use thecredit utilization calculatorto check your own number.
Checklist: Before You Ask for a Card on Your Existing Card
Check your current limit and utilisation. Aim to keep use low.
Pull your credit report and confirm there are no errors or missed dues.
Look for an upgrade option on your bank's app or website.
Check the new card's fee and what spend waives it.
Compare the travel benefit with how often you actually fly.
Check the eligibility income for the new card.
Apply to one card, then wait for the result.
Give consent only for the changes you want.
Common Mistakes to Avoid
Expecting the new card to share your old card's limit.
Applying to many travel cards in a few weeks.
Taking a card for lounge access you will not use.
Accepting an upgrade without checking the new annual fee.
Using a cash advance on a card to fund a purchase. Fees and interest start at once.
Ignoring the total limit the bank sees. A high existing balance can cut a new offer.
Related on benchmarksutra
FAQs
Can I get a credit card based on my existing credit card?
Not in the sense of using its limit. A bank assesses each new card on its own and counts the limits you already hold. A good history on your existing card helps your application, but approval is the bank's decision.
Does a new credit card share my existing card's limit?
Not by default. A new card account gets its own limit. Ask the issuer before you apply if you expect a shared limit, since the terms vary by bank.
Will a bank give me a card automatically because I hold one?
It cannot issue a card without your explicit consent. RBI's 2025 Directions prohibit unsolicited cards and unilateral upgrades.
Will my existing card limit reduce my new card limit?
It can. RBI requires banks to count your limits on other cards, so a new card may come with a smaller limit.
Can I ask my bank for an upgrade?
Yes. If your bank has a higher variant of your card, ask whether you qualify. The bank decides, and you must consent to the change.
Does applying for a second card hurt my credit score?
A credit card application can add a hard enquiry to your credit report. A few spread-out applications are usually less of a concern than many in a short window.
Is a cash advance against my card limit the same as a new card?
No. A cash advance is a withdrawal against your limit with fees and interest from the withdrawal date. Check the fee table in your bank's MITC before using it.
Official Sources and Editorial Note
Data checked as of: 9 November 2026
RBI (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025, updated as on 1 October 2026
https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=13155
RBI Complaint Management System (Ombudsman)
https://cms.rbi.org.in
HDFC Bank Credit Card MITC
https://www.hdfc.bank.in/content/dam/hdfcbankpws/in/en/personal-banking/discover-products/cards/credit-cards/personal-mitc/mitc-in-english.pdf
SBI Card most important terms and conditions
https://www.sbicard.com/en/most-important-terms-and-conditions.page
This article is written from official sources and does not rely on third-party wording.
Editorial note:We found no bank product page that sells a card against an existing card. Terms for upgrades and limit changes vary by bank, so ask your issuer. The limit table is our own illustration.