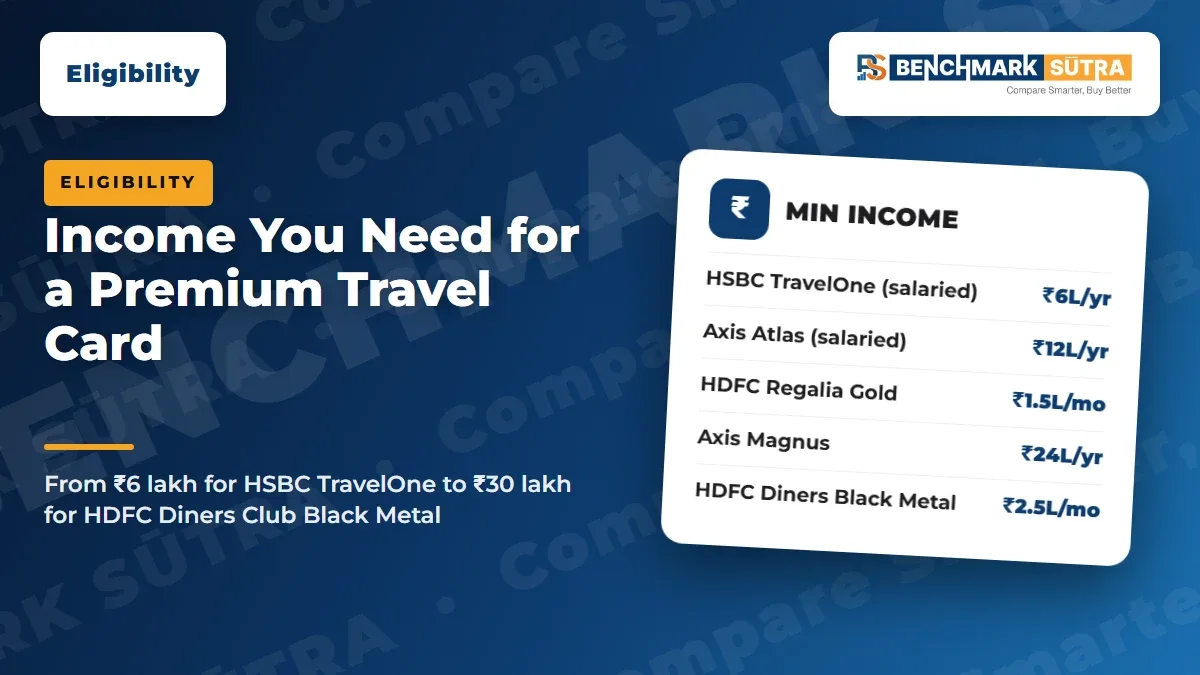
Travel cards start at ₹6 lakh a year, Axis Atlas needs ₹12 lakh, Magnus ₹24 lakh and Diners Black ₹30 lakh. Card-wise income, age and city rules from bank pages.
Quick Verdict
For a premium travel credit card in India, you usually need ₹6 lakh to ₹12 lakh a year for an entry travel card, ₹12 lakh to ₹18 lakh for a mid-premium card, and ₹24 lakh to ₹30 lakh or more for a super-premium card. Self-employed applicants often need a higher figure on their Income Tax Return than salaried applicants.
That is the short answer on the income required for premium credit card approval, based on bank pages as of November 2026. Banks call these figures indicative. Your credit report, existing loans and city also decide the outcome.
Income band (yearly) | Example travel cards | Official income bar |
|---|---|---|
No income figure published | Scapia Axis Bank | Residents aged 18–70; Axis lists no income figure |
₹6 lakh+ | HSBC TravelOne; BOBCARD Etihad Guest | ₹6 lakh salaried (TravelOne: ₹12 lakh self-employed) |
₹12 lakh+ | Axis Atlas; BOBCARD Etihad Guest Premium | ₹12 lakh net salaried (Atlas: ₹15 lakh self-employed) |
About ₹18 lakh+ | HDFC Regalia Gold | Gross monthly above ₹1.5 lakh; ITR above ₹18 lakh |
₹24 lakh+ | Axis Magnus | ₹24 lakh net salary or ITR |
₹30 lakh+ | HDFC Diners Club Black Metal | Net monthly above ₹2.5 lakh; ITR above ₹30 lakh |
₹36 lakh+ | HSBC Taj | ₹36 lakh salaried, ₹45 lakh self-employed (product page) |
Apply with HDFC: Check HDFC credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Apply with Axis: Check Axis credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Apply with BOBCARD: Check the BOBCARD Etihad Guest credit card
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Why Is There No Single Income Rule?
RBI does not set a minimum income for any credit card. Its credit card directions for banks ask issuers to assess credit risk using each applicant's independent financial means, and to count the limits you already hold on other cards.
So each bank sets its own bar for each card. For travel cards, the bar rises with three things the bank pays for: lounge visits, low forex markups and high-value reward points. A card that offers unlimited lounges and a 2% forex markup costs the bank more to run, so it looks for richer, lower-risk customers.
Our bank-wise guide Minimum Salary for a Credit Card in India covers entry-level cards. This guide covers the travel tier.
Premium Travel Card Income Requirements, Card by Card
These figures come from each bank's own product or eligibility page, checked in November 2026. Fees are plus GST.
Card | Salaried | Self-employed | Age | Annual fee and waiver |
|---|---|---|---|---|
HSBC TravelOne | ₹6 lakh a year | ₹12 lakh a year | 18–65 salaried; 25–65 self-employed | ₹4,999; free above ₹8 lakh yearly spend |
BOBCARD Etihad Guest | ₹6 lakh a year | Check BOBCARD | 21–60 | ₹2,500; waived at ₹3 lakh a year |
Axis Atlas | ₹12 lakh net a year | ₹15 lakh net a year | 18–70 | ₹5,000 |
BOBCARD Etihad Guest Premium | ₹12 lakh a year | Check BOBCARD | 21–60 | ₹5,000; waived at ₹5 lakh a year |
HDFC Regalia Gold | Gross monthly above ₹1.5 lakh (government: above ₹1 lakh) | ITR above ₹18 lakh | 21–60; 21–65 | ₹2,500; waived at ₹4 lakh a year |
Axis Magnus | ₹24 lakh net salary | ₹24 lakh net ITR | 18–70 | ₹12,500; waived on ₹25 lakh spend in the preceding year |
HDFC Diners Club Black Metal | Net monthly above ₹2.5 lakh | ITR above ₹30 lakh | 21–60; 21–65 | Check HDFC's current fee page |
HSBC Taj | ₹36 lakh (product page) | ₹45 lakh (product page) | 25–75 | ₹1,10,000; no waiver |
Two notes on reading this table:
Gross, net or ITR: HDFC's Regalia Gold criteria say gross monthly income, while its FAQ says net. Axis uses net annual income. If only your gross salary clears the bar, call the bank first.
Pages that disagree: HSBC's Taj MITC still shows ₹40 lakh salaried and ₹60 lakh self-employed and says the card is offered on invitation. Confirm the current rule with HSBC before applying.
What Else Decides Approval?
Income gets you to the door. These factors decide whether you walk in.
Your city
HSBC TravelOne and HSBC Taj are offered only in 21 listed cities, including Mumbai, Delhi NCR, Bengaluru, Chennai, Hyderabad, Pune, Kolkata, Ahmedabad, Jaipur and Kochi. If you live outside the list, you cannot apply even with a high income.
Your credit report
Banks see every loan and card on your bureau report. A ₹20 lakh salary with large EMIs can look weaker than a ₹15 lakh salary with none. Pull your free yearly credit report and fix errors first.
Your existing cards
RBI asks banks to count the limits you already have. Several high-limit cards can lower the limit, or the approval odds, on a new one.
Your banking relationship
Some premium cards are easier through your own bank. Axis Burgundy Private is the extreme case: it is gated by a ₹5 crore relationship value with Axis, not by income.
If you were turned down, read 5 Common Reasons Your Credit Card Was Rejected.
What If Your Income Is Below the Bar?
You still have routes to travel benefits.
A zero-fee travel card: the Scapia Axis Bank card has no joining or annual fee and lists nil forex markup. Axis lists residents aged 18–70 and no income figure. Lounge access needs ₹20,000 net spend in a billing cycle.
An entry travel card first: HSBC TravelOne and BOBCARD Etihad Guest start at ₹6 lakh a year.
An upgrade later: use a mid-range card from the same bank, pay in full, and ask for an upgrade once your income rises. HDFC has a credit card upgrade service page for existing cardholders.
Better paperwork: if you are self-employed, file ITR every year on time with your true income. Our guide How to Get a Credit Card as a Freelancer explains the documents.
More approval tips are in 7 Hacks to Boost Your Credit Card Approval Chances.
Is a Higher-Income Card Worth It for You?
Qualifying is not the same as benefiting. A premium travel card pays off only if you travel enough to use it.
Your travel pattern | What to look for |
|---|---|
1–2 domestic trips a year | A low-fee card with a few domestic lounge visits |
Several international trips a year | Low forex markup: Regalia Gold and Magnus list 2%; Scapia Axis and BOBCARD Etihad Premium list nil |
Loyal to one airline | An airline co-brand such as BOBCARD Etihad Guest |
Heavy spend, flexible travel | A transferable-points card such as Atlas or Magnus, if you clear its fee waiver |
Also check spend gates. Regalia Gold's domestic lounges now need ₹60,000 of spend in the previous calendar quarter. Points only matter if you redeem them well; see Reward Points 101.
Checklist
Find the eligibility page of the exact card you want.
Check whether the bar is gross monthly, net monthly, net annual or ITR income.
Check the age band, especially if you are close to 60 and salaried.
Check that your city is on the bank's list.
Pull your credit report and add up your EMIs.
Keep two years of ITR ready if self-employed.
Work out whether your yearly spend clears the fee waiver.
Compare forex markup and lounge spend gates, not just the welcome offer.
Common Mistakes to Avoid
Mistake 1: Applying for the top card first
A rejection adds a hard enquiry to your report. Apply for a card whose bar you clear with room to spare.
Mistake 2: Reading gross as net
If the bank means net income and you only clear it on gross, expect a rejection.
Mistake 3: Ignoring the city list
HSBC's travel cards are limited to listed cities. Check before you apply.
Mistake 4: Inflating income on the form
Banks check payslips, Form 16 or ITR. A mismatch can lead to rejection.
Mistake 5: Paying a premium fee for unused perks
Unlimited lounges are worth nothing if you fly twice a year. Match the card to your trips.
FAQs
How much income do I need for a premium travel credit card?
On bank pages as of November 2026, entry travel cards start at ₹6 lakh a year, mid-premium cards at ₹12 lakh to ₹18 lakh, and super-premium cards at ₹24 lakh to ₹36 lakh or more.
What income is needed for the Axis Atlas card?
Axis lists net annual income of ₹12 lakh for salaried and ₹15 lakh for self-employed applicants, aged 18–70.
What income is needed for HDFC Regalia Gold?
HDFC lists gross monthly income above ₹1.5 lakh for salaried applicants (above ₹1 lakh for government employees) and ITR above ₹18 lakh for the self-employed.
What income is needed for Axis Magnus?
Axis lists a net salary of ₹24 lakh a year or a net ITR of ₹24 lakh.
Is there a travel card with no income requirement?
Axis lists no income figure for the Scapia Axis Bank card, only residency and age 18–70. Approval still depends on the bank's checks.
Does RBI set a minimum income for credit cards?
No. RBI asks banks to assess each applicant's independent financial means; each bank sets its own criteria.
Official Sources and Editorial Note
Data checked as of: 5 November 2026
RBI (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025
https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=13155
HSBC TravelOne Credit Card
https://www.hsbc.bank.in/credit-cards/products/travelone/
Axis Bank Atlas Credit Card
https://www.axis.bank.in/cards/credit-card/axis-bank-atlas-credit-card
Axis Bank Magnus Credit Card
https://www.axis.bank.in/cards/credit-card/axis-bank-magnus-credit-card
Scapia Axis Bank Credit Card
https://www.axis.bank.in/cards/credit-card/scapia-axis-bank-credit-card
HDFC Bank Regalia Gold eligibility
https://www.hdfc.bank.in/credit-cards/regalia-gold-credit-card/eligibility
HDFC Bank Diners Club Black Metal Edition eligibility
https://www.hdfc.bank.in/credit-cards/diners-club-black-metal-edition-credit-card/eligibility
HDFC Bank Credit Card MITC, updated 31 October 2026 (fees and waivers)
https://www.hdfc.bank.in/content/dam/hdfcbankpws/in/en/personal-banking/discover-products/cards/credit-cards/personal-mitc/mitc-in-english.pdf
HDFC Bank credit card upgrade
https://www.hdfc.bank.in/credit-cards/services/credit-card-upgrade
BOBCARD Etihad Guest
https://bobcard.co.in/credit-card-types/bobcard-etihad-guest
BOBCARD Etihad Guest Premium
https://bobcard.co.in/credit-card-types/bobcard-etihad-guest-premium
HSBC Taj Credit Card
https://www.hsbc.bank.in/credit-cards/products/taj/
HSBC Taj Important Terms and Conditions (MITC)
https://www.hsbc.bank.in/content/dam/hsbc/in/documents/credit-cards/taj/hsbc-taj-important-terms-and-conditions.pdf
This article is written from official sources and does not rely on third-party wording.
Editorial note:
Eligibility figures are indicative and change often; several bank pages disagree with their own MITC or FAQ. BOBCARD figures are carried from our checks of BOBCARD's official pages earlier this week. Always confirm the latest criteria with the bank before applying.