Four zero forex markup credit cards a first-timer can actually get, from Scapia and IDFC FIRST Bank, with fees, access rules, rewards and a ₹ cost example.
Quick Verdict
Several credit cards in India havezero forex markup, and a first-timer can get four of them: the Scapia Axis Bank card, the Scapia Federal card, IDFC FIRST Millennia and IDFC FIRST WOW!. IDFC FIRST Bank says all its credit cards now carry zero forex markup. As of November 2026, the Scapia Axis card (78/100) is the best zero forex markup credit card for a beginner who books travel online.
If you have no income proof or credit history, the FD-backed IDFC FIRST WOW! (73/100) is the card you are most likely to get. For a broader list including premium cards, read ourbest credit cards for international travel.
Card | Forex markup | Joining / annual fee | Beginner access | Score |
|---|---|---|---|---|
Scapia Axis Bank | Nil | No joining or annual fee | Residents aged 18 to 70 | 78/100 |
Scapia Federal | Zero | No joining or annual fee (per Scapia) | Open application | 78/100 |
IDFC FIRST Millennia | Zero | Lifetime free | Income ₹3 lakh+ | 77/100 |
IDFC FIRST WOW! | Zero | Lifetime free | FD of ₹20,000+, no income proof | 73/100 |
Apply with Federal/Scapia:Check the Scapia Federal credit card
Apply with Axis Bank:Check Axis Bank credit cards
How Much Does Forex Markup Cost a First-Time Traveller?
A forex markup is a percentage the bank adds when you pay in a foreign currency. Axis Bank, for example, lists 3.5% of the transaction value on cards such as ACE, Neo, Horizon and Select. GST at 18% applies on top, so 3.5% really costs about 4.13%. On a first trip abroad, the saving is easy to work out.
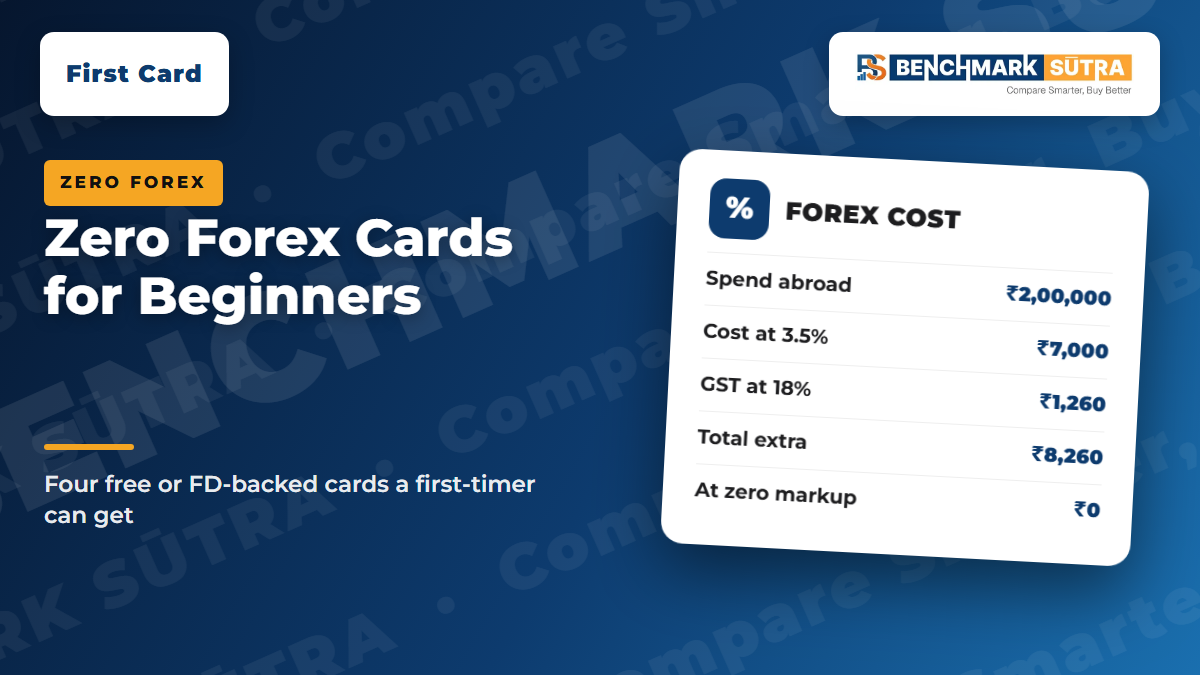
Spend abroad | Cost at 3.5% | GST at 18% | Total extra | Cost at zero markup |
|---|---|---|---|---|
₹50,000 | ₹1,750 | ₹315 | ₹2,065 | ₹0 |
₹1,00,000 | ₹3,500 | ₹630 | ₹4,130 | ₹0 |
₹2,00,000 | ₹7,000 | ₹1,260 | ₹8,260 | ₹0 |
That ₹8,260 on a ₹2,00,000 trip is more than most annual fees. Try your own numbers in theforex markup calculator.
Which Credit Cards Have Zero Forex Markup in India?
We checked issuer pages for cards a first-timer can realistically apply for. Premium cards such as Axis Burgundy Private also carry no markup, but they are invite-only or need a high relationship value, so they are not beginner cards.
Scapia Axis Bank Credit Card
Benchmarksutra Score:78/100 — B Tier
Axis terms list no joining fee, no annual fee, nil forex markup and nil DCC markup. One application gives a Mastercard and a RuPay card.
Rewards: 10 Scapia Coins per ₹100 on the Mastercard, with 5 coins equal to ₹1, so 2% in value. Bookings on the Scapia app earn 20 coins, or 4%. Coins redeem only on the app.
Lounge access needs ₹20,000 of net spend in the billing cycle.
It launched on 3 September 2026, so its track record is short. Full terms are in ourScapia Axis launch explainer.
Scapia Federal Credit Card
Benchmarksutra Score:78/100 — B Tier
Scapia lists no joining or annual fee and zero forex markup, with a choice of lounge access or up to ₹1,000 back at domestic airports.
This is Scapia's own description of the card, not a Federal Bank page, so confirm the terms when you apply.
We have written about the catch in the zero-forex pitch: readwhy the 0% forex perk has a catch.
IDFC FIRST Millennia
Benchmarksutra Score:77/100 — B Tier
Lifetime free with no spend condition. Zero forex markup, four railway lounge visits a quarter on ₹20,000 spend, and movie discounts.
Rewards: 3X (about 0.375%) on most spends and 10X (about 1.25%) on dining, travel and international spends since 18 June 2026. Each redemption costs ₹99 + GST.
Annual income of ₹3 lakh or more is the stated criterion.
IDFC FIRST WOW!
Benchmarksutra Score:73/100 — B Tier
An FD-backed card: minimum FD of ₹20,000 with IDFC FIRST Bank, ages 18 to 80, and no income proof or credit history needed. The limit is at least 100% of the FD, and the FD keeps earning interest.
Lifetime free, with zero forex markup. Rewards are modest at 4 points per ₹200 (about 0.5%).
No lounge access.
If you are new to credit, see ourbeginner's guide to using credit cards.
Which Zero Forex Card Should a Beginner Pick?
Match the card to your situation, not to the highest score:
You book flights and hotels on an app and want no fee:Scapia Axis or Scapia Federal. Remember that coins stay inside the Scapia app.
You want one card for daily spend and trips:IDFC FIRST Millennia, which has no fee condition and 10X on international spends since 18 June 2026.
You have no income proof or credit history:IDFC FIRST WOW!, backed by an FD of at least ₹20,000. Your deposit keeps earning interest.
You want lounges abroad:none of these four is built for it. Scapia and Millennia offer domestic or railway lounge access only, so a premium card may suit you later.
Whichever you choose, spend within your means and clear the bill in full. A zero-markup card saves money only if you avoid interest.
Zero Forex Markup Credit Card Benchmarksutra Scores
Card | Score | Tier | Best for |
|---|---|---|---|
Scapia Axis Bank | 78/100 | B Tier | Free travel card for app-based bookers |
Scapia Federal | 78/100 | B Tier | Free card with a lounge or cashback choice |
IDFC FIRST Millennia | 77/100 | B Tier | Everyday card with zero forex and railway lounges |
IDFC FIRST WOW! | 73/100 | B Tier | First card against an FD, no income proof |
See how these are built in theBenchmarksutra Credit Card Score methodology.
What Zero Forex Markup Does Not Cover
Zero markup means the bank adds no separate forex charge. Your foreign purchase is still converted to rupees at the applicable exchange rate, as IDFC FIRST Bank's own FAQ clarifies. Three traps remain:
Paying in rupees abroad.A merchant that offers to charge you in INR is using dynamic currency conversion. Always choose the local currency. OurHDFC ForexPlus card postshows another way banks price foreign spend.
The network you hold.Acceptance depends on Visa, Mastercard or RuPay; compare them inVisa vs Mastercard vs RuPay vs Amex.
Other fees.IDFC FIRST tells you to read the MITC for other charges, such as redemption fees and interest if you carry a balance.
Checklist
Confirm "zero forex" on the issuer page or MITC, not only in an ad.
Check joining and annual fees, and any spend condition.
Check how you will earn and redeem rewards abroad.
Make sure your card network is accepted where you are going.
Choose the local currency at every foreign terminal.
Set up app alerts and international usage controls before you fly.
Pay the full bill; interest costs more than any forex saving.
Common Mistakes to Avoid
Assuming every "travel card" has zero forex. Many charge 3.5%.
Choosing INR when a terminal offers to convert for you.
Applying for a premium card you will not qualify for, which adds a hard enquiry for nothing.
Ignoring coin or point redemption limits, such as Scapia coins that redeem only in its app.
Carrying only one card abroad. Keep a backup network.
Related on benchmarksutra
FAQs
Which credit cards have zero forex markup in India?
Among cards a beginner can get, the Scapia Axis Bank card, the Scapia Federal card and IDFC FIRST Bank cards such as Millennia and WOW! list zero forex markup. IDFC FIRST says this applies across all its credit cards.
Which is the best zero forex markup credit card for a first-timer?
We rate the Scapia Axis Bank card highest at 78/100, because it has no joining or annual fee. If you lack income proof, IDFC FIRST WOW! against an FD of ₹20,000 is easier to get.
Is zero forex markup really free?
The bank adds no markup, but the currency is still converted at the applicable rate and other fees, such as redemption fees, may apply. Check the MITC.
Does GST apply to forex markup?
Yes. GST at 18% applies on a markup, so a 3.5% markup costs about 4.13% in total. A zero-markup card avoids both.
Can I get a zero forex card without income proof?
IDFC FIRST WOW! states that no income proof or credit history is needed, but it requires a minimum FD of ₹20,000 with the bank.
Should I pay in rupees or the local currency abroad?
Pay in the local currency. Converting at the merchant's terminal is dynamic currency conversion and can add its own markup.
Are premium zero-forex cards a good idea for beginners?
Usually not. Cards like Axis Burgundy Private carry no markup but are for private-banking clients. Start with a free card and move up later.
Official Sources and Editorial Note
This article is written from official sources and does not rely on third-party wording.
We may earn a commission from some links on this page. It never affects our scores.