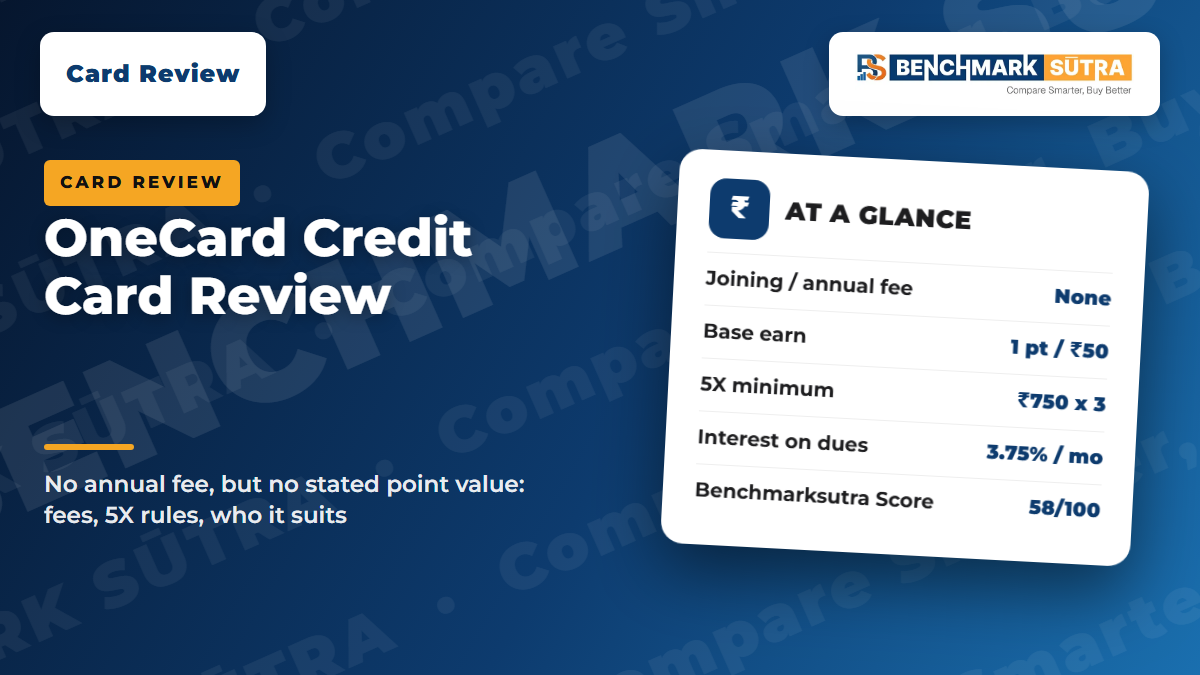
OneCard has no joining or annual fee, but no stated point value, a forex markup and 45% a year interest. Fees, rewards and who it suits.
Quick Verdict
Is the OneCard credit card worth it?Only as a free, app-run card for someone who spends steadily across at least three categories and does not mind that the terms never say what a reward point is worth. We score it58/100, which is "Avoid unless niche use case".
This onecard credit card review is built from OneCard's own pages and the issuing banks' terms, and our view is mixed. The "No Joining Fees" and "No Annual Fees" claim on the product page is plain and welcome, and the in-app controls are good. But the Federal Bank terms we read give no rupee value for a reward point, so the headline "5X rewards on top 2 spend categories" cannot be turned into a percentage. The same MITC charges 45% a year (3.75% a month) on unpaid dues and keeps the forex markup rate inside a fee-schedule image. A card that does not state its own earn rate is asking you to trust the marketing. We areResearched, not Tested: we read the terms and have not used the card.
One more point before you apply: OneCard is issued by different banks. Its page lists BOBCARD, CSB Bank, Federal Bank, SBM Bank, South Indian Bank and Indian Bank, and each has its own terms. Check which bank issues your card.
Item | OneCard (as of November 2026) |
|---|---|
Joining / annual fee | None, per OneCard's page |
Base earn | 1 point per ₹50; point value not stated |
Bonus | 5X on top 2 categories if you spend in at least 3, minimum ₹750 each |
Interest on dues | 45% a year, 3.75% a month (Federal MITC) |
Cancel within 6 months | ₹3,000 charge |
Lounge access | None listed |
Benchmarksutra Score:58/100 — Avoid unless niche use case
Try it with your own numbers:Credit Card Reward Value Calculator
What Does the OneCard Credit Card Cost?
OneCard's page says "No Joining Fees", "No Annual Fees" and "No Rewards Redemption Fees". That is the card's strongest point. The costs sit elsewhere.
Charge | What the terms say |
|---|---|
Interest on unpaid dues | 45% a year or 3.75% a month, plus GST (Federal MITC, effective 1 August 2024) |
Over-limit fee | 2.5% of the over-limit amount or ₹500, whichever is higher; only if the over-limit control is on |
Cancel within 6 months of activation | ₹3,000 |
Rent via the OneCard app | 2% convenience fee, no points |
Rent via third-party apps | 1% transaction fee plus the app's own fee |
Transfers to wallets or bank accounts | 1% on cumulative monthly transfers of ₹10,000 or more |
Forex markup | Applies; the rate is in the fee schedule, so check it in your app |
Run your own bill through thecredit card interest calculatorto see what 3.75% a month does to a carried balance. If you pay in full every month, interest never touches you. Our explainer onwhy paying only the minimum is dangerouscovers the trap.
How Do OneCard Rewards Actually Work?
The base earn is 1 reward point for every ₹50 spent, with fractional points on smaller amounts (₹25 earns 0.5 points). Rent, money transfers, cash withdrawals, wallet loads and fuel earn nothing.
The 5X bonus has conditions. You must spend in at least three categories in a month, and since 6 January 2025 you need at least ₹750 in each of those three. The top two categories then earn 5X, credited on the 10th of the next month. For education, bills and utilities, and insurance, the incremental 5X points stop once they total 25,000.
Rule | What it means for you |
|---|---|
1 point per ₹50 | ₹10,000 of spend earns 200 points |
5X on top 2 categories | ₹10,000 in those two categories earns 1,000 points, if the 3-category rule is met |
₹750 minimum per category | A month with spend in only two categories earns no bonus |
Point value | Not stated; the terms say the bank may change the conversion rate |
Because there is no stated rupee value, you cannot call this "10% back" or any other percentage. Use thereward value calculatorwith the value you actually see in the app before you count on it. Our guide onhow to calculate the real value of a reward pointshows why this matters, andreward points vs cashbackhelps you choose.
Redemption and Expiry
There is no fee to redeem. You can use "Pay With Points" on past transactions, but only those less than two months old, or redeem on offers in the app. Points have lifetime validity, with exceptions: if the card is unused for more than 365 days the accrued points are nullified, and they are forfeited on closure or the cardholder's death. The bank can also withhold rewards where it suspects misuse.
App, Add-ons and Perks
The product page highlights in-app control over transaction limits, domestic and international use, online and offline use, and contactless payments. EMIs are managed on a dashboard, and "MyFamily" lets you share your limit with family members, each with their own card. Onboarding is described as fully digital, with activation in under five minutes.
What is not listed: airport lounge access, travel insurance, dining or movie offers. This is a utility card, not a perks card. Add-on cardholders earn points on the same transactions as the primary holder.
Who Is the OneCard Best For?
Freshers and beginners
This is the best fit. No joining or annual fee, digital onboarding and strong in-app controls make it a low-risk first card. Pay in full every month; seethe best first credit card in Indiafor the alternatives. The catch: the product page did not show eligibility criteria we could read, so approval is not guaranteed.
Middle-aged families
The MyFamily add-on is useful if you want one limit shared across the household. Families who spread spend over groceries, bills, school fees and insurance can meet the three-category rule easily, but remember the 25,000-point cap on the bills, education and insurance bonus.
Travellers and frequent flyers
Weak fit. There are no lounges, and a forex markup applies. Check the rate in your app and test it in theforex markup calculatorbefore using the card abroad.
Professionals (CA, lawyers, doctors)
Use it as a secondary no-fee card for day-to-day spends, not as a business card. The terms say the bank may check for business or non-personal use and can cancel cards and withhold rewards if it finds it.
Senior citizens and retirees
A fully app-driven card may be harder for anyone who prefers branch support. If your family manages it for you, the add-on feature helps. Compare withcashback cards for senior citizensbefore deciding.
OneCard Benchmarksutra Scores
Card | Score | Tier | Best for |
|---|---|---|---|
OneCard | 58/100 | Avoid unless niche use case | Beginners wanting a free app-run card |
Our method is explained inhow we rate Indian credit cards. The card earns most points on Fee Value (13/15) and loses them on Benefits (3/10), Hidden Costs (4/10) and Redemption (5/10). Where the official documents are silent, such as point value and eligibility, we score conservatively. If OneCard publishes a rupee value per point, the Reward Value score could rise. See alsohow we review credit cards.
Checklist Before You Apply
Find out which bank will issue your card, and read that bank's MITC.
Look for the rupee value of one reward point in the app and note the date.
Check the forex markup in the fee schedule if you spend abroad.
Confirm you spend at least ₹750 in three categories each month before counting on 5X.
Set up auto-pay for the full amount so the 3.75% monthly interest never applies.
Remember the ₹3,000 charge if you cancel within six months.
Common Mistakes to Avoid
Assuming "5X" means a high cashback percentage. The base is 1 point per ₹50 and the point value is not stated.
Paying rent through the card. It earns nothing and costs 1% or 2%.
Spending in only two categories and wondering why the bonus never appears.
Leaving the card unused for a year. Points are nullified after 365 days of inactivity.
Carrying a balance. At 3.75% a month the interest outruns any reward.
Related on benchmarksutra
Credit cards in India: every benchmarksutra guide in one place
SBI Card PRIME Credit Card Review: Benefits, Fees, Who It Suits
FAQs
Is the OneCard credit card free?
OneCard's page says no joining fee and no annual fee. Other charges, such as interest, over-limit fees and a ₹3,000 charge for cancelling within six months of activation, still apply.
Which bank issues the OneCard?
The page lists BOBCARD, CSB Bank, Federal Bank, SBM Bank, South Indian Bank and Indian Bank as partner banks. Each has its own terms, so read the one that applies to your card.
How do OneCard rewards work?
You earn 1 point per ₹50. The top two categories earn 5X if you spend in at least three categories that month, with a ₹750 minimum in each. The 5X points post on the 10th of the next month.
What is a OneCard reward point worth?
The terms we read do not state a rupee value and say the bank may change the conversion rate. Check the value shown in the app before you plan around it.
Does OneCard charge forex markup?
The terms say a forex markup fee applies to foreign-currency transactions and to rupee transactions at merchants or gateways based outside India. The rate is in the fee schedule, so check it in your app.
Do OneCard points expire?
Points have lifetime validity, except that they are nullified if the card is unused for more than 365 days and forfeited on account closure.
Does OneCard have airport lounge access?
None is listed on the product page or in the terms we read. If lounges matter, look at a different card.
Official Sources and Editorial Note
This article is written from official sources and does not rely on third-party wording.