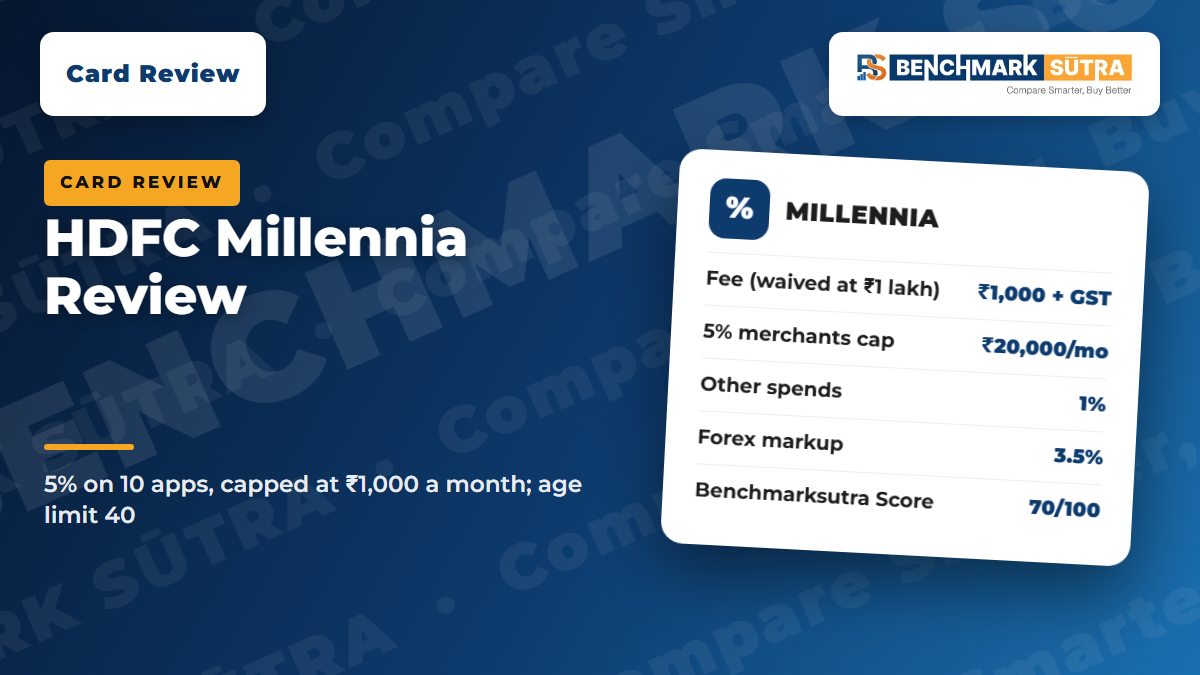
Is the HDFC Millennia worth it? 5% on 10 apps capped at ₹1,000 a month, ₹1,000 fee waived at ₹1 lakh, age cap 40, 3.5% forex. Score 70/100.
Quick Verdict
The HDFC Millennia credit card is worth it for under-40 online shoppers who spend about ₹30,000 or more a month and can reach the ₹1 lakh yearly spend that waives the ₹1,000 fee.For anyone else, the 5% headline is smaller than it looks. This HDFC Millennia credit card review is based on HDFC's own pages and terms as of November 2026. We researched the card from official documents; we have not tested it.
Here is what the terms say that the banner does not. The 5% applies to ten named merchants only and stops at 1,000 CashPoints a month, so the most it can pay is ₹1,000 on ₹20,000 of spend. Everything else earns 1%, with its own separate cap of 1,000 CashPoints. HDFC's eligibility box also sets a maximum age of 40 for new applicants, and fuel, rent, government payments, wallet loads and EMI earn nothing. Forex costs 3.5% per HDFC's MITC. Above about ₹1.2 lakh a month, extra spend earns you nothing more on this card.
Apply with HDFC:Check HDFC credit cards
Try it with your own numbers:Credit Card Reward Value Calculator
Item | HDFC Millennia |
|---|---|
Fee | ₹1,000 + taxes joining and renewal |
Renewal waiver | Spend ₹1 lakh or more in a year before the renewal date |
Earn rate | 5% on 10 online merchants, 1% on other spends, paid as CashPoints worth ₹1 each |
Monthly caps | 1,000 CashPoints on the 5% bucket and 1,000 on the 1% bucket |
Milestone | ₹1,000 gift voucher or 1 domestic lounge visit on ₹1 lakh spend in a calendar quarter |
Eligibility | Age 21 to 40; salaried net income above ₹35,000 a month; self-employed ITR above ₹6 lakh a year |
Benchmarksutra Score | 70/100, B Tier |
Benchmarksutra Score:70/100 — B Tier
Is the HDFC Millennia Credit Card Worth It?
It is worth it when your spend lands in the sweet spot: enough to clear the ₹1 lakh waiver, with a good slice going to the ten partner merchants. HDFC's T&C lists them as Amazon, BookMyShow, Cult.fit, Flipkart, Myntra, Sony LIV, Swiggy, Tata CLiQ, Uber and Zomato. Each CashPoint is worth ₹1 against your statement.
Monthly spend | Split (our assumption) | CashPoints a month | Value a year | Quarterly milestone |
|---|---|---|---|---|
₹15,000 | ₹6,000 on the 10 merchants, ₹9,000 other | 300 + 90 = 390 | ₹4,680 | Missed (₹45,000 a quarter) |
₹40,000 | ₹15,000 on the 10 merchants, ₹25,000 other | 750 + 250 = 1,000 | ₹12,000 | Met: ₹1,000 voucher, about ₹4,000 a year |
₹1,20,000 | ₹20,000 on the 10 merchants, ₹1,00,000 other | 1,000 + 1,000 = 2,000 | ₹24,000 | Met: about ₹4,000 a year |
That is about 2.6% back at ₹15,000 a month, 2.5% at ₹40,000 (3.3% with the voucher) and 1.7% at ₹1.2 lakh. The rate falls at the top because both buckets hit their caps. At ₹3 lakh a month you would still earn ₹2,000, under 1%. The examples ignore rounding, since CashPoints are earned on multiples of ₹100. Run your own mix in ourreward value calculatorand readreward points vs cashbackif the CashPoint model is new to you.
Fees, Waiver and Eligibility
Item | Detail |
|---|---|
Joining and renewal fee | ₹1,000 + applicable taxes (₹1,180 at 18% GST) |
Renewal waiver | ₹1 lakh or more spent in a year before the renewal date |
Fee offset | HDFC's page says you get Reward Points equal to the fee amount when you pay it |
Forex markup | 3.5% (HDFC MITC, October 2026) |
Salaried | Age 21 to 40, net monthly income above ₹35,000 |
Self-employed | Age 21 to 40, ITR above ₹6 lakh a year |
Interest-free period | Up to 50 days from the date of purchase |
The fee is easy to avoid. ₹1 lakh a year is about ₹8,333 a month. If you will not reach that, the card does not pay for itself: at 1% you would need ₹1.18 lakh of spend just to earn back ₹1,180. Check the break-even in ourannual fee breakeven calculatorand readhow credit card fee waivers workfor how banks count qualifying spend.
How the Rewards Work
Rule | Detail |
|---|---|
5% merchants | Amazon, BookMyShow, Cult.fit, Flipkart, Myntra, Sony LIV, Swiggy, Tata CLiQ, Uber, Zomato; non-EMI spends only |
5% cap | 1,000 CashPoints per calendar month (₹20,000 of spend) |
1% bucket | All other spends; 1,000 CashPoints per calendar month (₹1,00,000 of spend) |
Excluded from earning | Fuel, rent, government, EMI, wallet loads (MCC 6540), card fees, cash advances |
Third-party education | Earns nothing; paying the school or college directly does earn |
Gift and prepaid card loads | The 5% terms page says 1%, the 1% terms page says no earn; do not rely on it |
Redemption | ₹1 per CashPoint against the statement; minimum 500 and maximum 3,000 CashPoints a month |
Posting | Spends settled in a month post in the first week of the next month |
Two traps stand out. First, 5% is calculated on the merchant's terminal or merchant ID, so a purchase that does not carry the right ID does not qualify. Second, Uber earns 5% only on travel spends coded as MCC 4121. For the general logic behind such gaps, seewhy you sometimes earn zero reward points.
Milestone Voucher, Lounge and Other Benefits
Quarterly milestone:spend ₹1 lakh net in a calendar quarter (January to March, April to June, and so on) and pick either a ₹1,000 gift voucher or one domestic lounge visit. EMI principal counts; SmartEMI does not.
No standing lounge access:HDFC ended complimentary domestic lounge access on Millennia from 1 December 2023. The only lounge route is the quarterly milestone.
SmartBuy and PayZapp:HDFC advertises up to 10% extra cashback on 200+ brands via SmartBuy or PayZapp Shop; these follow the platforms' own terms. SeeHDFC SmartBuy offers for November 2026.
Fuel surcharge waiver:1% on transactions of ₹400 to ₹5,000, up to ₹250 a statement cycle. Fuel spends earn no CashPoints.
Dining:an extra 10% off on Swiggy Dineout with code HDFCCARDS, under its own terms.
Controls:card controls through NetBanking, the HDFC app, MyCards, PayZapp and WhatsApp Banking.
There is no welcome benefit listed on the product page. For international trips, 3.5% on foreign spends makes this a poor choice; check your own numbers in theforex markup calculator.
Who Does the HDFC Millennia Suit?
Freshers and beginners
A reasonable first card if you are salaried above ₹35,000 a month and under 40, and your spending is mostly Amazon, Flipkart, Swiggy and Zomato. HDFC's page does not publish a minimum credit score or a rule for people with no history, so approval is not guaranteed. Compare options inhow to compare credit cards in India.
Middle-aged families
Only if you are 40 or younger. Family spending on groceries, fuel and utilities earns just 1% (fuel earns nothing), so the 5% list does little for a household that shops offline. The ₹1,000 quarterly voucher helps once monthly spend crosses about ₹33,000.
Travellers and frequent flyers
Not a fit. There is no standing lounge access, the quarterly lounge visit needs ₹1 lakh of spend, and forex costs 3.5%. A travel card will do better.
Professionals (CA, lawyer, doctor)
Self-employed applicants need an ITR above ₹6 lakh a year and must be 40 or under. If you pay personal bills and online subscriptions on the card, the waiver is easy. The card is for personal use; it is not a business expense tool.
Senior citizens and retirees
New applications are not open to you: the maximum age on HDFC's page is 40. If you already hold a Millennia, the 1% bucket and ₹1 CashPoints still work, and the ₹1 lakh waiver is the number to watch. For other HDFC options seethe best HDFC credit cards.
HDFC Millennia Benchmarksutra Score
Our score uses a fixed 100-point framework. The use case here is an online-shopper cashback card. Seehow we score credit cards.
Category | Score | Why |
|---|---|---|
Reward Value | 13/20 | 5% on 10 apps (cap 1,000 CP), 1% elsewhere (cap 1,000 CP), ₹1 per CashPoint |
Fee Value | 13/15 | ₹1,000 + GST, waived at ₹1 lakh yearly spend; ₹1,000 voucher per ₹1 lakh quarter |
Redemption Quality | 7/10 | ₹1 per CP on statement; min 500, max 3,000 a month; only ₹0.30 on travel |
Use-Case Fit | 13/15 | Online-shopper cashback: strong for Amazon, Flipkart, Swiggy, Zomato, Uber users |
Eligibility and Accessibility | 7/10 | ₹35,000 net monthly income; salaried age capped at 40 |
Benefits and Perks | 5/10 | Quarterly choice of ₹1,000 voucher or 1 domestic lounge; no welcome benefit |
Hidden Costs and Conditions | 5/10 | 5% stops at ₹20k a month; nil on fuel, rent, wallets, EMI; 3.5% forex |
Bank and User Experience | 7/10 | HDFC MyCards, SmartBuy; point value not protected on upgrades from Millennia |
Total | 70/100 | B Tier |
HDFC Millennia Benchmarksutra Scores at a Glance
Card | Score | Tier | Best for |
|---|---|---|---|
HDFC Millennia | 70/100 | B Tier | Under-40 online shoppers spending ₹30,000+ a month |
IDFC FIRST Millennia | 77/100 | B Tier | Everyday spenders who want no age cap; see theIDFC FIRST Millennia review |
Checklist Before You Apply
Are you 40 or younger, with net income above ₹35,000 a month (salaried) or an ITR above ₹6 lakh?
Will you spend ₹1 lakh or more in the year to waive the ₹1,000 fee?
Add up monthly spend on Amazon, Flipkart, Myntra, Swiggy, Zomato, Uber, Tata CLiQ, BookMyShow, Sony LIV and Cult.fit.
Keep fuel, rent, wallet loads and EMI on another card; they earn nothing here.
Plan to reach ₹1 lakh in a calendar quarter if you want the voucher or lounge visit.
Redeem CashPoints against the statement every month so they never pile up unused.
Read the latest HDFC MITC and T&C before you apply.
Common Mistakes to Avoid
Reading 5% as a flat return. It stops at ₹20,000 of spend a month.
Putting EMI purchases on the card and expecting 5% on them. EMI spends earn nothing.
Loading wallets or paying rent on the card for points. Neither earns.
Missing the ₹1 lakh waiver and paying ₹1,180 for ₹1,000 or less of rewards.
Counting SmartEMI towards the quarterly milestone. Only EMI principal paid counts.
Using the card abroad at a 3.5% markup.
Assuming the card is open to every age. HDFC lists 21 to 40.
Related on benchmarksutra
Credit cards in India: every benchmarksutra guide in one place
HDFC Infinia Credit Card Review: Benefits, Fees, Who It Suits
HDFC Bank ForexPlus Card Issuance Fee Waiver: What It Covers and What You Still Pay
HDFC PIXEL Times Credit Card Launched: Rush vs Move Fees, Rewards and Who Should Apply
Marriott Bonvoy HDFC Credit Card Anniversary Offer: Up to 30,000 Bonus Points — What to Check
ICICI Sapphiro Credit Card Review: Benefits, Fees, Who It Suits
FAQs
Is the HDFC Millennia credit card worth it?
It is worth it if you are 40 or younger, spend ₹30,000 or more a month and use the ten partner merchants. The ₹1,000 fee is waived at ₹1 lakh of yearly spend, which most such users reach.
What is the HDFC Millennia annual fee?
The joining and renewal fee is ₹1,000 plus taxes. HDFC waives the renewal fee if you spend ₹1 lakh or more in a year before the renewal date.
Which merchants earn 5% on HDFC Millennia?
Amazon, BookMyShow, Cult.fit, Flipkart, Myntra, Sony LIV, Swiggy, Tata CLiQ, Uber and Zomato. EMI purchases do not qualify, and the 5% is capped at 1,000 CashPoints a month.
What is the maximum cashback on HDFC Millennia?
Each calendar month you can earn up to 1,000 CashPoints on the 5% merchants and 1,000 on other spends, so 2,000 CashPoints (₹2,000) in total, plus the quarterly milestone voucher.
Does HDFC Millennia have lounge access?
Not as a standing benefit. HDFC ended complimentary domestic lounge access in December 2023. You can choose one domestic lounge visit instead of the ₹1,000 voucher when you spend ₹1 lakh in a calendar quarter.
What is the eligibility for HDFC Millennia?
Salaried applicants need net monthly income above ₹35,000 and an age of 21 to 40. Self-employed applicants need an ITR above ₹6 lakh a year and the same age range.
What is the forex markup on HDFC Millennia?
HDFC's MITC lists a 3.5% foreign currency markup for this card family. Our forex calculator can show what that costs on your trips.
What is a CashPoint worth on Millennia?
One CashPoint is worth ₹1 as statement cashback. CashPoints are earned on spends in multiples of ₹100.
Official Sources and Editorial Note
https://www.hdfc.bank.in/credit-cards/millennia-credit-card/fees-and-charges
https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=13155&Mode=0
Card rules follow RBI's "Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025 (updated as on 1 October 2026)". Terms can change; HDFC's MITC says non-regulatory changes need 30 days' notice.
This article is written from official sources and does not rely on third-party wording.
We may earn a commission from some links on this page. It never affects our scores.