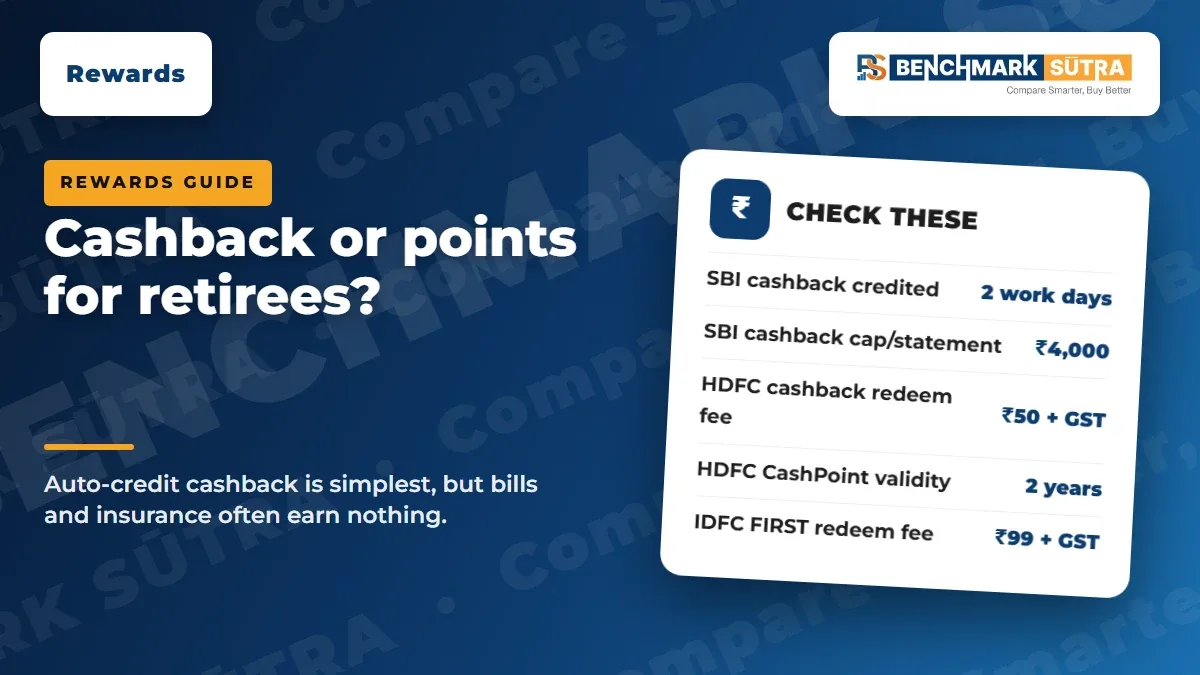
Auto-credit cashback beats points for most retirees: nothing to redeem or expire. But check exclusions on bills and insurance first. Official terms, November 2026.
Quick Verdict
Yes, for most retirees a cashback card is less hassle than a points card. The best kind credits cashback to your card account automatically, so there is nothing to redeem, no catalogue to read, and no points to expire. Points cards can pay more, but only if you remember to redeem, pay the redemption fee, and use the points before they lapse.
When you choose a cashback credit card for senior citizens, check one thing above the headline rate: are your real spends excluded? Many cashback cards pay nothing on utility bills, insurance premiums, fuel and railway tickets, which are a large part of many retirees' budgets. This guide compares the two types using official bank terms, as of November 2026.
Question | Auto-credit cashback | Cashback you must redeem | Reward points |
|---|---|---|---|
Do you need to do anything? | No | Yes, a redemption request | Yes, choose and redeem |
Example from official terms | CASHBACK SBI Card: credited within 2 working days of statement | HDFC CashPoints: ₹50 + GST per cashback redemption request | IDFC FIRST: ₹0.25 a point, ₹99 + GST per redemption |
Expiry | SBI says earned cashback does not expire | HDFC CashPoints: 2 years on most cards | IDFC FIRST WOW!: 24 months |
Easy to check value? | Yes, shown in ₹ on the statement | Mostly; ₹ value per point varies by use | No; value depends on how you redeem |
Apply with SBI: Check SBI credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Apply with HDFC: Check HDFC credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Why Is Cashback Simpler for Retirees?
A retiree's card is usually not a hobby. It pays for medicines, groceries, a few online orders and the occasional trip. What matters is that the card returns something without effort and never costs more than it gives.
Points cards ask for more work:
Redeeming: you log in, choose a voucher, product, airline miles or statement credit, and confirm.
Fees: many banks charge a fee on each redemption. IDFC FIRST charges ₹99 + GST on its WOW! card, for example.
Changing values: one point can be worth different amounts depending on what you redeem it for. Our guide on the real value of one reward point shows the maths.
Expiry: HDFC's Most Important Terms and Conditions say Reward Points and CashPoints are valid for 2 years from the date of accumulation on most cards. Points you forget are points you lose.
Auto-credit cashback skips all four. The rupee amount appears on your statement and reduces what you owe.
Not All "Cashback" Is Automatic
The word cashback on a card's name does not always mean automatic credit. There are two kinds.
Automatic statement credit
SBI Card's FAQ for the CASHBACK SBI Card says cashback is credited automatically within two working days of the statement date, shows on the monthly statement, needs no redemption, and does not expire. That is the low-effort model. We cover how and when credits land in How Credit Card Cashback Is Credited.
Cashback you have to claim
Some cards earn "CashPoints" that you convert to cashback yourself. HDFC's MITC (version 4.18, October 2026) sets a processing fee of ₹50 + GST per cashback redemption request on most of its cards, with a minimum redemption amount, for example ₹500 for Millennia, Freedom and MoneyBack. It also says a cashback credit is not treated as payment of your last statement, so you still need to pay that bill in full.
That is not a bad card. It is simply more steps, and one more thing to remember each month.
The Catch: Exclusions on a Retiree's Spends
Cashback is only simple if your spends actually earn it. SBI Card's revision notice for the CASHBACK SBI Card, effective 1 April 2026, lists these exclusions:
Spend type | Earns cashback on CASHBACK SBI Card? | Why it matters to retirees |
|---|---|---|
Online shopping (non-excluded) | Yes, 5%, up to ₹2,000 per statement | Online medicine and grocery orders may qualify, by merchant code |
Offline shops (non-excluded) | Yes, 1%, up to ₹2,000 per statement | Local chemist and supermarket spends |
Utility bills | No | Electricity, phone and gas are regular costs |
Insurance premiums | No | Health insurance premiums can be large after 60 |
Fuel, rent, wallet loads | No | Fuel gets a 1% surcharge waiver on ₹500 to ₹3,000, up to ₹100 a statement |
Railways, tolls, government payments | No | Train tickets and tax payments earn nothing |
School and education, jewellery, digital gaming | No | Grandchildren's fees and gold purchases earn nothing |
Merchant EMI and Flexipay EMI | No | Large purchases on EMI earn nothing |
The card costs ₹999 a year plus GST, waived when you spend ₹2 lakh or more in the preceding year, according to SBI Card's MITC. Caps work the same way across most cashback cards: see The Truth About 5% Cashback Cards.
A Worked Example for a Retired Couple
Take an illustrative monthly spend of ₹20,000: ₹4,000 on online orders, ₹6,000 at local shops and the chemist, ₹5,000 on utility bills and ₹5,000 on an insurance premium spread across the year. These figures are our assumptions, not bank data.
Card type (official rates) | Monthly reward | Yearly reward | Effort and cost |
|---|---|---|---|
CASHBACK SBI Card: 5% online, 1% offline; utilities and insurance excluded | ₹200 + ₹60 = ₹260 | ₹3,120 | None; ₹999 + GST fee, waived at ₹2 lakh of yearly spends (this couple spends ₹2.4 lakh; confirm with SBI Card which spends count) |
Points card at 0.5% value (IDFC FIRST WOW!: 4 points per ₹200, ₹0.25 a point), on the ₹10,000 of shop and online spend | About ₹50 | About ₹600, less ₹99 + GST per redemption | Redeem once a year; lifetime free; points valid 24 months |
The point is not which brand wins. The point is that only ₹10,000 of the ₹20,000 earns anything on either card, because half the budget goes to bills and insurance. Before choosing, add up how much of your own spending is actually eligible. The effective reward rate guide shows how.
When Does a Points Card Make Sense After 60?
You travel and like planning. Points that turn into flights or hotel stays can be worth more than cashback. Read Reward Points 101 first.
A family member manages redemptions. If your son or daughter enjoys this, a points card can work, but the card and app should stay with you.
The card is free and the points never matter. An FD-backed card such as IDFC FIRST WOW! is lifetime free; small points are a bonus, not the reason to hold it.
If none of these fit, choose automatic cashback, or a simple card with no annual fee.
Checklist
Confirm the cashback is credited automatically, not on request.
List your monthly spends and mark which ones the card excludes.
Check the cashback cap per statement or month.
Work out whether you will cross the fee-waiver spend, or pay the fee.
On a points card, note the redemption fee, minimum and expiry.
Pay the full bill by auto-debit; interest wipes out any reward.
Recheck terms once a year; banks revise rewards with notice.
Common Mistakes to Avoid
Mistake 1: Judging a card by its top rate
5% sounds good, but if your largest spends are bills and insurance, you may earn far less.
Mistake 2: Assuming "cashback" means automatic
Some cashback must be requested, with a fee and a minimum. Read the terms.
Mistake 3: Letting points expire
Set a yearly reminder to redeem, or choose a card where you never have to.
Mistake 4: Treating cashback as your bill payment
HDFC says a cashback credit is not a payment towards the last statement. Pay the bill in full anyway.
Mistake 5: Answering "points expiring" calls
Calls and SMS about expiring points are a common fraud route. Check your points only in the bank's own app or website.
FAQs
Is a cashback card simpler than a points card for seniors?
Usually yes, if the cashback is credited automatically. There is nothing to redeem and nothing to expire, and the value shows in rupees on your statement.
Do cashback cards give cashback on utility bills and insurance?
Often not. The CASHBACK SBI Card, for example, excludes utilities, insurance, fuel, rent, wallet loads, railways, education and more, as of its April 2026 revision.
Does credit card cashback expire?
It depends on the card. SBI Card says CASHBACK SBI Card cashback does not expire, while HDFC CashPoints are valid for 2 years on most cards.
Is there a fee to redeem cashback or points?
Sometimes. HDFC charges ₹50 + GST per cashback redemption request on most cards, and IDFC FIRST charges ₹99 + GST per points redemption on WOW!. Auto-credit cashback has no redemption step.
What is the annual fee on the CASHBACK SBI Card?
₹999 plus GST, waived if you spend ₹2 lakh or more in the preceding year, per SBI Card's MITC as of November 2026.
Should retirees get a points card at all?
Only if you will redeem regularly, ideally for travel, or if the card is free and the points are a minor bonus.
Official Sources and Editorial Note
Data checked as of: 5 November 2026
SBI Card: CASHBACK SBI Card FAQs (rates, caps, auto-credit, no expiry, fuel surcharge waiver)
https://www.sbicard.com/en/faq/cashback-sbi-card-faq.page
SBI Card: Revision in the benefits of CASHBACK SBI Card, effective 1 April 2026 (caps and exclusions)
SBI Card cashback revision notice (PDF)
SBI Card Most Important Terms and Conditions (annual fee and waiver)
https://www.sbicard.com/en/most-important-terms-and-conditions.page
HDFC Bank Most Important Terms and Conditions, version 4.18, October 2026 (cashback redemption fee, minimums, point validity)
HDFC Bank MITC (PDF)
IDFC FIRST Bank FIRST WOW! Credit Card (reward rate, point value, redemption fee, validity)
https://www.idfcfirst.bank.in/credit-card/wow
This article is written from official sources and does not rely on third-party wording.
Editorial note:
The worked example uses assumed spends. Whether a merchant earns cashback depends on its merchant category code, which card networks set and can change. Rates, caps and fees change; check the bank's current terms before applying.