10X reward points is not 10% back. How to turn 5X and 10X into a real rupee rate, with HDFC Freedom, IDFC FIRST Millennia and Biz Power maths, plus the caps and unlock rules.
Quick Verdict
"10X reward points" means a card gives you ten times its base number of points on certain spends, such as partner apps, travel or tax payments. It does not mean 10% back. What a 10X offer is worth depends on two numbers banks put in small print: the base rate it multiplies, and the rupee value of one point.
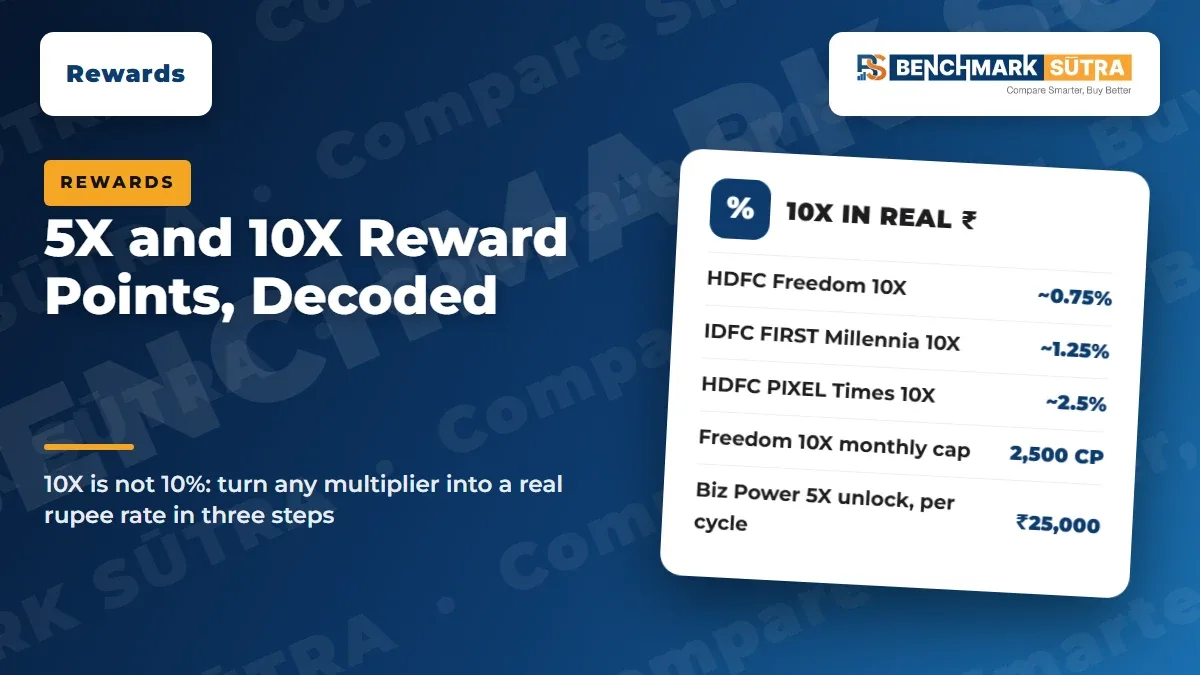
That is the short answer for anyone weighing an accelerated reward points credit card. HDFC Freedom's 10X works out to about 0.75%. IDFC FIRST Millennia's 10X is about 1.25%. The same label can mean very different money.
Card (as of November 2026) | Base earn | Accelerated earn | Value of 1 point | Accelerated rate in ₹ |
|---|---|---|---|---|
HDFC Freedom | 1 CashPoint per ₹200 | 10 per ₹200 on 5 apps | ₹0.15 | About 0.75% |
IDFC FIRST Millennia | 3 points per ₹200 | 10 per ₹200 on dining, travel, international | ₹0.25 | About 1.25% |
HDFC PIXEL Times | 2 points per ₹200 | 10X on 2 chosen brand packs | ₹0.25 | About 2.5% |
HDFC Biz Power | 5 points per ₹200 | 5X on tax, GST, bills, ads, travel | ₹0.15 to ₹0.65 | Depends on redemption |
The rule to remember: effective rate = points per ₹100 × rupee value of a point. The "X" only tells you how many points, not what they are worth.
What Does 10X Reward Points on a Credit Card Mean?
Every rewards card has a base rate, the points you earn on ordinary spends. An accelerated rate multiplies that on chosen categories or merchants. "5X" is five times the base and "10X" is ten times.
But banks are not consistent about what "1X" is. Two examples show why you must read the numbers, not the label.
HDFC Freedom: 1 CashPoint per ₹200 on most spends and 10 per ₹200 on BigBasket, BookMyShow, OYO, Swiggy and Uber. Here 10X really is ten times the normal rate.
IDFC FIRST Millennia: 3 points per ₹200 on most spends, 10 per ₹200 on dining, travel and international spends, and 1 per ₹200 on utilities, insurance, railways and FASTag. The "10X" is ten times the utility rate, but only about 3.3 times the rate on everyday shopping.
So a "10X" card can be worth less, or more, than a "5X" card. You only know once you convert it to rupees.
How to Convert 5X or 10X Into a Real Percentage
Use this three-step method.
Find points per ₹100. HDFC Freedom's 10 per ₹200 is 5 per ₹100.
Find the rupee value of one point for the redemption you will actually use. Freedom's CashPoint is worth ₹0.15 as cashback.
Multiply. 5 × ₹0.15 = ₹0.75 per ₹100, or 0.75%.
If the bank does not publish a rupee value, you cannot work out the rate with confidence. SBI Card's SimplyCLICK documents we read list 10 points per ₹100 at partners, but do not state a rupee value per point. AU Bank's CS card is similar. In such cases, we treat the headline as unproven until you see the catalogue price.
For more on point values, read How to Calculate the Real Value of 1 Reward Point.
The Fine Print on Accelerated Rewards
Monthly and cycle caps
Almost every accelerated rate is capped. HDFC Freedom caps its 10X at 2,500 CashPoints a calendar month, which is ₹375 at ₹0.15. HDFC Biz Power caps its 5X at 7,500 points per statement cycle. SBI SimplyCLICK caps partner points and other-online points at 10,000 a month each. AU CS caps its accelerated points at 5,000 a cycle.
Minimum spend to unlock
Some accelerators only switch on after a threshold. HDFC says Biz Power's 5X applies only if you spend at least ₹25,000 in the statement cycle, excluding income tax and GST payments.
Transaction limits
HDFC also says Biz Power awards points only on the first two income tax payments and the first two GST payments in each billing cycle.
Channel rules
Many accelerators count only when you pay through a set channel: the partner's own app, the bank's portal such as HDFC SmartBuy, or a specific government payment site. Paying the same merchant another way earns the base rate. For SmartBuy's own multipliers and caps, see HDFC SmartBuy Offers, November 2026.
Merchant codes
Banks decide the category by the merchant category code, not by what you bought. A restaurant billed under a different code may not earn the dining multiplier. See Why You Sometimes Earn Zero Reward Points.
Worked Example: A CA's Practice Card
Take a chartered accountant with an HDFC Biz Power card who spends ₹1 lakh a month on it. ₹30,000 goes on 5X categories (software subscriptions bought through SmartBuy BizDeals, Google and Meta ads, bill payments) and ₹70,000 on other business spends. The ₹25,000 unlock is met by the non-tax spends.
HDFC's page does not spell out whether "5X" means 25 points per ₹200 in total or 5 extra base units on top. We assume 25 per ₹200 in total, which is five times the base.
Spend | Points earned | As statement cashback (₹0.15) | On business catalogue (up to ₹0.65) |
|---|---|---|---|
₹70,000 at base (5 per ₹200) | 1,750 | ₹262.50 | Up to ₹1,137.50 |
₹30,000 at 5X (25 per ₹200) | 3,750 | ₹562.50 | Up to ₹2,437.50 |
Total a month | 5,500 | ₹825 (0.83%) | Up to ₹3,575 (3.6%) |
The same points are worth more than four times as much depending on how you redeem them. Here the redemption choice matters more than the multiplier. HDFC also needs at least 2,500 points to redeem against your statement, and points lapse after two years.
A professional on the AU CS card sees the same pattern: 8 points per ₹100 on dining, travel, tax and software against 2 on retail is a 4X boost, but AU does not publish a rupee value per point, so the real return depends on its catalogue.
When Is a 5X or 10X Card Worth It?
When your spend already sits in the boosted category. A 10X on food apps helps only if you order often.
When the cap is above your likely spend. Otherwise you earn base points after the cap.
When the point value is published and high. ₹0.25 or more a point turns 10X into a useful rate.
When the redemption you will use is the valuable one. Catalogue or travel values often beat cashback, but only if you want what is on offer.
For a structured way to compare, see Reward Rate vs Effective Reward Rate. For using points on flights, read Reward Points 101.
Checklist
Write down the base earn rate in points per ₹100.
Find the accelerated rate and the exact merchants or categories.
Find the rupee value of one point for the redemption you will use.
Multiply points per ₹100 by the point value to get the real percentage.
Check the monthly or cycle cap and the spend needed to hit it.
Check any unlock threshold or transaction-count limit.
Check the channel: partner app, bank portal or government site.
Note redemption fees and minimums, such as 2,500 points on Biz Power.
Common Mistakes to Avoid
Reading 10X as 10%. HDFC Freedom's 10X is about 0.75%.
Comparing multipliers across banks. "1X" means different things at each bank.
Ignoring caps. Spend above the cap earns only the base rate.
Missing unlock conditions. Biz Power's 5X needs ₹25,000 of non-tax spend in the cycle.
Paying outside the right channel. The same merchant via a different app may earn base points.
Redeeming at the lowest value. Cashback can be worth a fraction of catalogue or travel redemptions.
Assuming an unpublished point value. If the bank does not state it, check the catalogue first.
FAQs
What does 10X reward points on a credit card mean?
It means ten times the card's base points on certain spends. The real value depends on the base rate and the rupee value of each point, not the 10X label.
Is 10X reward points the same as 10% cashback?
No. HDFC Freedom's 10X is about 0.75% back and IDFC FIRST Millennia's is about 1.25%, as of November 2026.
How do I calculate the value of accelerated reward points?
Multiply the points you earn per ₹100 by the rupee value of one point. For example, 5 points per ₹100 at ₹0.15 a point is 0.75%.
Are accelerated reward points capped?
Usually yes. HDFC Freedom caps its 10X at 2,500 CashPoints a month, and HDFC Biz Power caps its 5X at 7,500 points a statement cycle.
Which business spends earn 5X on HDFC Biz Power?
HDFC lists income tax and GST payments, bill payments, Google and Meta ads, Reliance Digital, and hotel and flight bookings. The 5X needs ₹25,000 of non-tax spend in the cycle.
Why did I not get the accelerated points I expected?
Common reasons are a cap already reached, the wrong payment channel, a merchant code outside the category, or an unmet spend threshold.
Official Sources and Editorial Note
Data checked as of: 5 November 2026
HDFC Bank Freedom Credit Card and terms
Official page
Freedom terms (PDF)
HDFC Bank Biz Power Credit Card
Official page
HDFC Bank PIXEL Times Credit Card
Official page
IDFC FIRST Millennia Credit Card
Official page
May 2026 notice (PDF)
SimplyCLICK SBI Card reward terms
Reward terms (PDF)
AU Small Finance Bank CS Credit Card reward terms
Reward terms (PDF)
This article is written from official sources and does not rely on third-party wording.
Editorial note:
Earn rates, caps, point values and partner lists change often. Check the bank's current reward terms before you plan spends around a multiplier.