Yes, you can get a first credit card after 60. FD-backed cards go up to 75 at HDFC and 80 at IDFC FIRST, no income proof. Routes, steps and first-year tips.
Quick Verdict
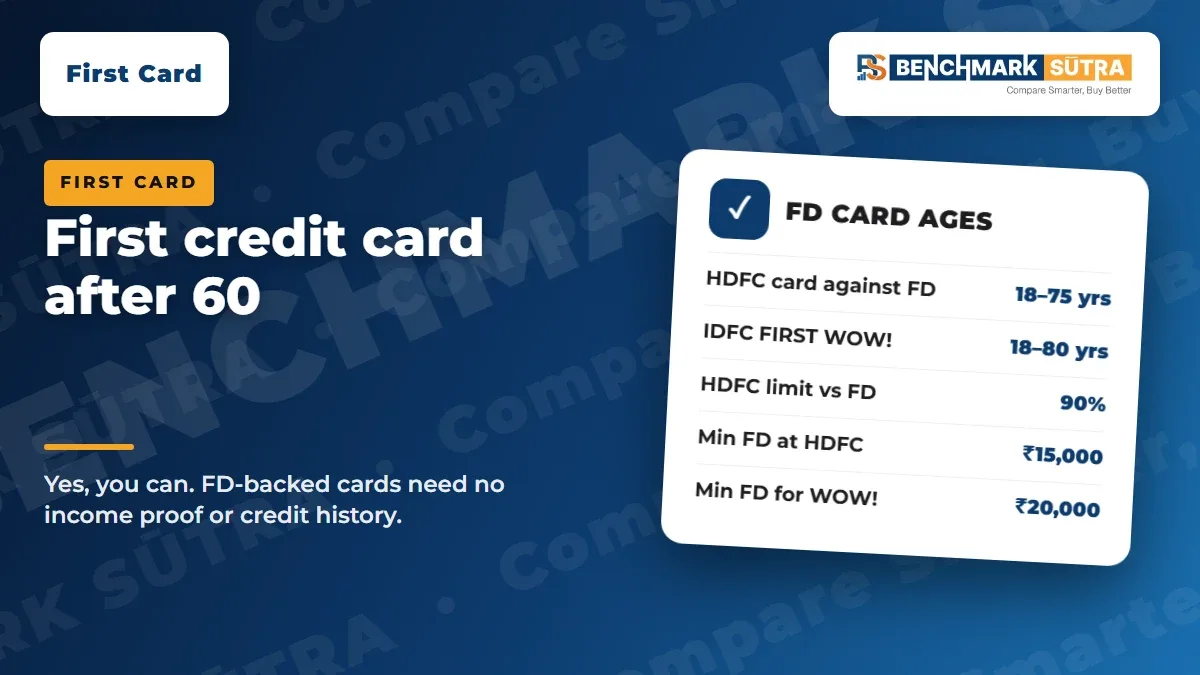
Yes, you can get your first credit card after the age of 60 in India. The surest route is a card against a fixed deposit: HDFC Bank issues one up to age 75 and IDFC FIRST Bank's FIRST WOW! up to 80, with no income proof needed. An ordinary card on pension income is possible too, but many cards stop at 60, 65 or 70, and a first-time applicant has no credit history for the bank to check.
This guide is for people applying for a first credit card after 60: never had a card, perhaps never taken a loan. It covers what having no credit history means, which route to pick, the step-by-step application, and how to use the card safely in the first year. All terms come from official bank and RBI pages, as of November 2026.
Route | Age range on official page | Needs credit history? | Needs income proof? |
|---|---|---|---|
HDFC Bank credit card against FD | 18 to 75 | Not stated as a requirement | No |
IDFC FIRST WOW! (FD-backed) | 18 to 80 | No | No |
Axis Bank credit card against FD | 18 and above; no upper age shown | Not stated as a requirement | No |
Ordinary card on pension (e.g. HDFC Freedom) | 21 to 60 salaried; 21 to 65 self-employed | Bank checks your bureau record | Yes |
Add-on card on a family member's card | Set by the main card's bank | Not for you | Not for you |
Apply with Axis: Check Axis credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Apply with HDFC: Check HDFC credit cards
Disclosure: this is an affiliate link. BenchmarkSutra may earn a commission if you apply through it, at no extra cost to you. It does not change our analysis.
Why Is a First Card After 60 Harder?
Two things work against a first-time applicant over 60, and neither is about your character or savings.
1. Age bands on ordinary cards
Banks set age limits card by card. HDFC's Freedom card, for example, takes salaried applicants from 21 to 60 and self-employed applicants from 21 to 65. SBI Card's issuance policy uses 21 to 65 for salaried and 25 to 70 for self-employed applicants. Axis Bank's general primary-cardholder range is 18 to 70. If you are 66 and retired, many ordinary cards are already closed to you.
2. No credit history
RBI asks banks to "independently assess the credit risk" of every applicant, taking into account their independent financial means. A credit report is the main tool for that. If you have never held a loan or card, the bureaus may have little or nothing on you. That is not a bad score; it is a blank page. But a blank page gives a bank little to approve an unsecured card on.
An FD-backed card solves both problems. Your deposit is the security, so the bank does not need income proof or a long credit record.
Which First Card Route Should You Choose?
Your situation | Best first route | Reason |
|---|---|---|
Aged 60 to 75, have FDs, want your own card | FD-backed card at your own bank | No income proof; limit tied to your FD |
Aged 75 to 80 | IDFC FIRST WOW! | The only official page we found that goes up to 80 |
Under the bank's age limit, steady pension, prefer not to lock an FD | Ordinary card at the bank where your pension is credited | The bank already sees your monthly pension |
Want a card only for occasional use, with family oversight | Add-on card on your son's, daughter's or spouse's card | No application in your name; the main cardholder is liable |
Note that an add-on card does not build a credit history in your own name the way your own card does, because RBI places the liability on the main cardholder. If you want your own record, choose your own card. Age limits for every route are compared in Can Pensioners Get a Credit Card?
FD-Backed Cards Compared
These terms are from each bank's official page as of November 2026.
Feature | HDFC Bank | Axis Bank | IDFC FIRST WOW! |
|---|---|---|---|
Age | 18 to 75 | 18 and above | 18 to 80 |
Minimum FD | ₹15,000 | Not stated on the page we read | ₹20,000 |
Credit limit | 90% of the FD | Up to 80% to 90% of the FD | At least 100% of the FD |
FD rules | Tenure of at least 1 year; PAN updated; tax-saver, NRI, minor-held, sweep-in, non-withdrawal and already-pledged FDs not eligible | Indian with valid PAN; FD can be booked through any UPI app | Singly held FDs only |
Cards offered | Not named on the page | IndianOil Easy, Privilege Easy, MY Zone Easy | FIRST WOW! |
Annual fee | Check HDFC's current terms | Depends on the card | Lifetime free |
FD interest | Continues while pledged | Check with Axis | FD keeps earning interest |
For the full cost maths on WOW!, read The Best FD-Backed Card: IDFC WOW Math Explained.
How much should you put in the FD?
Think about your largest likely monthly spend, not the biggest limit you can get. At HDFC's 90%, a ₹20,000 FD gives an ₹18,000 limit. At IDFC FIRST's 100%, a ₹20,000 FD gives at least ₹20,000. HDFC says you can select several eligible FDs to raise the limit. Keep your emergency and medical money in a separate FD that is not pledged.
How to Apply: Step by Step
Step 1: Check your credit report first
Under RBI's 2016 directions, each credit bureau must give you one free full credit report, including your score, every calendar year. Get yours. If it is empty, go FD-backed. If it shows a loan you do not recognise, dispute it before you apply.
Step 2: Start with your own bank
Your pension or savings bank already holds your KYC and FDs. HDFC lets you apply online by selecting your FD, or at a branch with ID proof, address proof and the FD details. Axis says existing customers can skip the video KYC call that new customers must complete.
Step 3: Read the Key Fact Statement
RBI requires every application to come with a one-page Key Fact Statement showing the interest rate and charges. If something is unclear, ask the branch before you sign. If you are rejected, the bank must give you the specific reasons in writing.
Step 4: Activate within 30 days
If you do not activate a new card within 30 days, RBI requires the bank to ask for OTP consent and, without it, close the card at no cost within seven working days. Activate only through the bank's app, net banking or official helpline.
Step 5: Set it up before the first spend
Register for SMS alerts, set auto-debit for the full amount due, and keep international use switched off. RBI requires new cards to start with online, international and contactless use turned off until you switch them on.
Your First Year With the Card
Use it a little, every month. One or two regular spends, such as a phone bill or the chemist, paid in full, start a clean record.
Stay well below the limit. Do not treat the limit as a target.
Never pay only the minimum. Interest starts and the interest-free period on new spends ends.
Do not withdraw cash on it. Use your debit card for cash.
Keep the FD in place. Breaking a pledged FD affects the card. Ask your bank first.
More basics are in Credit Card 101: A Beginner's Guide.
Checklist
Download your free credit report from a bureau.
Pick the route: FD-backed, pension-based or add-on.
Check the age range on the exact card's official page.
For FD cards: use a singly held FD of at least 1 year that is not tax-saver or already pledged.
Keep emergency savings outside the pledged FD.
Read the Key Fact Statement for interest and fees.
Activate within 30 days through official channels only.
Set auto-debit for the full amount due and keep international use off.
Common Mistakes to Avoid
Mistake 1: Applying to several banks at once
Each application leaves an enquiry on your report. Apply at one bank, starting with your own. See 5 Common Reasons Your Credit Card Was Rejected.
Mistake 2: Using a joint FD
Many retired couples hold joint FDs. IDFC FIRST accepts only singly held FDs for WOW!, so check first.
Mistake 3: Pledging all your savings
A big FD gives a big limit you do not need, and locks money you may need for health costs.
Mistake 4: Letting a caller "help" you apply
Apply only through the bank's website, app or branch. Never share an OTP with a caller.
Mistake 5: Giving up after one rejection
Read the written reasons and move to an FD-backed card. Low-income approval tips are in 7 Ways to Boost Approval Chances.
FAQs
Can I get my first credit card after the age of 60?
Yes. FD-backed cards are the easiest route: HDFC Bank accepts applicants up to 75 and IDFC FIRST WOW! up to 80, with no income proof.
Can I get a credit card with no credit history at 65?
Yes, through an FD-backed card. IDFC FIRST says WOW! needs no credit history, and HDFC and Axis say their FD cards need no income proof.
What is the maximum age for a credit card in India?
It differs by card. HDFC Freedom goes to 60 for salaried applicants, Axis lists 70 for primary cardholders, HDFC's FD card goes to 75 and IDFC FIRST WOW! to 80.
How much FD do I need for a credit card?
₹15,000 at HDFC and ₹20,000 for IDFC FIRST WOW!, as of November 2026. The limit is 90% of the FD at HDFC and at least 100% at IDFC FIRST.
Will an FD-backed card build my credit score?
It is a credit card in your name, so paying it on time builds your record. Note that a new card is reported to bureaus only after you activate it.
Is an add-on card better than my own card after 60?
An add-on is simpler, but the liability stays with the main cardholder, so it does not build your own record the same way. Choose your own card if you want independence.
Does my FD still earn interest when it backs a card?
Yes. HDFC says interest on a pledged FD is not stopped, and IDFC FIRST says the WOW! FD keeps earning interest.
Official Sources and Editorial Note
Data checked as of: 5 November 2026
HDFC Bank credit card against FD (age, minimum FD, ineligible FDs, limit, income proof, FD interest)
https://www.hdfc.bank.in/credit-cards/credit-card-against-fd
HDFC Bank Freedom Credit Card eligibility
https://www.hdfc.bank.in/credit-cards/freedom-credit-card/eligibility
Axis Bank credit card against fixed deposit (age, PAN, limit, income documents, video KYC)
https://www.axis.bank.in/cards/credit-card/credit-card-against-fixed-deposit
IDFC FIRST Bank FIRST WOW! Credit Card
https://www.idfcfirst.bank.in/credit-card/wow
SBI Card policy for the issuance and conduct of credit cards (2023)
SBI Card issuance policy (PDF)
Reserve Bank of India (Commercial Banks – Credit Cards and Debit Cards: Issuance and Conduct) Directions, 2025, updated as on 1 October 2026
https://www.rbi.org.in/Scripts/BS_ViewMasDirections.aspx?id=13155
RBI circular: Enhancing Security of Card Transactions (2020)
https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=11788&Mode=0
RBI circular on free annual credit report from credit information companies (2016)
https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=10590
This article is written from official sources and does not rely on third-party wording.
Editorial note:
Age limits, FD minimums and fees change and differ by card. Banks approve cards at their own discretion. Confirm the latest terms with your bank before applying.