Are credit card welcome benefits worth it? We compare seven welcome gifts with their fees, spend windows and real rupee value, as of November 2026.
Quick Verdict
Credit card welcome benefits are worth it only when their rupee value is higher than the fee you pay to get them, and you were going to make the required spend anyway.Most are smaller than they look: in the cards we checked, the welcome gift ranged from ₹75 against a ₹500 fee to about ₹2,320 against a ₹1,000 fee, and many need a spend within 30 to 90 days.
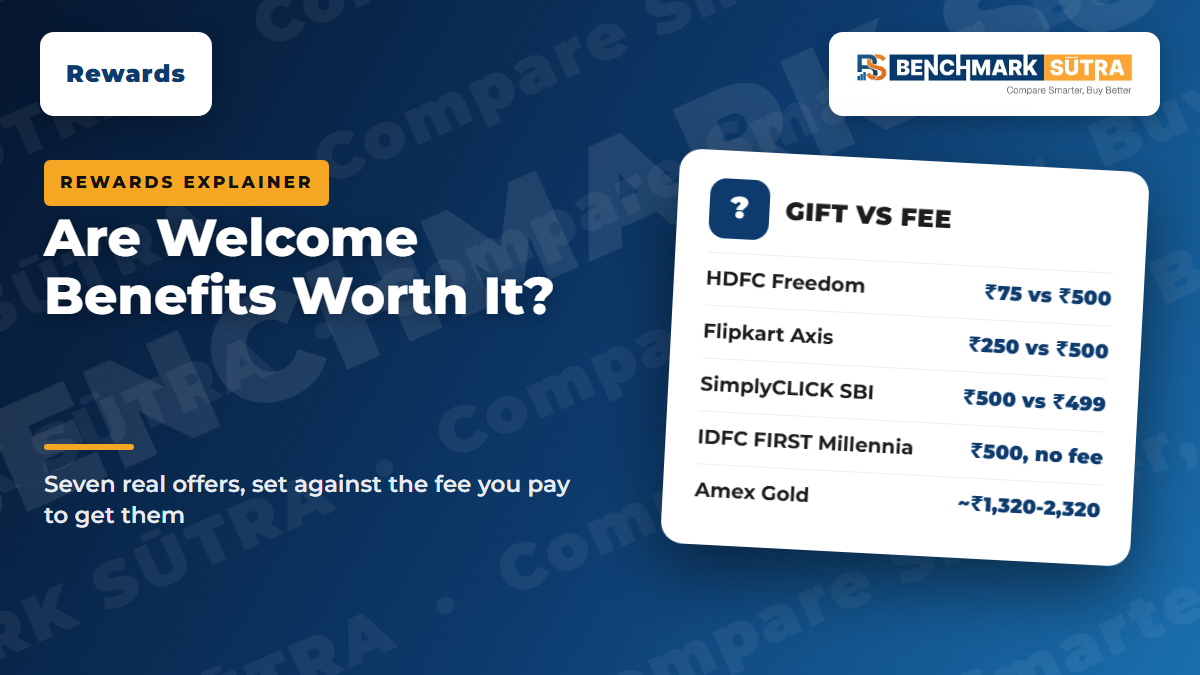
Here is our view, as of November 2026. A welcome benefit is a marketing line, not a feature. HDFC Freedom's 500 CashPoints are worth ₹75 at ₹0.15 each, against a ₹500 plus taxes fee. Flipkart Axis gives a ₹250 voucher against a ₹500 fee. SimplyCLICK SBI gives a ₹500 Amazon Pay gift card against a ₹499 plus GST fee, which is roughly even. The best ones are the free ones: IDFC FIRST Millennia is lifetime free and gives a ₹500 voucher on ₹5,000 spend in 30 days, so there is no fee to beat. We did not use any of these cards; this is a read of the issuers' own pages and terms.
For a first-time card holder with no credit history, the rule is simple: pick the card for its everyday fit and fee, and treat the welcome benefit as a small extra. Never spend more than you planned to reach it.
Card | Welcome benefit | What you must do | Fee it sits against |
|---|---|---|---|
IDFC FIRST Millennia | ₹500 voucher | Spend ₹5,000 in 30 days | Lifetime free |
SimplyCLICK SBI | ₹500 Amazon Pay gift card | Pay the fee | ₹499 + GST |
Tata Neu Plus HDFC | 499 NeuCoins (₹1 at Tata brands) | Pay the first-year fee | About ₹499 (reverses the fee) |
Tata Neu Infinity HDFC | 1,499 NeuCoins | Pay the fee on a paid card | ₹1,499 + taxes |
Amex Gold | 4,000 points (about ₹1,320 to ₹2,320) | Pay the fee; spend ₹10,000 in 90 days | ₹1,000 + taxes in year 1 |
Flipkart Axis | ₹250 Flipkart voucher | Pay the fee | ₹500 |
HDFC Freedom | 500 CashPoints (₹75) | Pay the joining fee | ₹500 + taxes |
Test any offer with thereward value calculatorand theannual fee breakeven calculator. These cards are examples of how welcome benefits work, not a ranking or a recommendation.
What Counts as a Credit Card Welcome Benefit?
A welcome benefit is anything you get for joining or for early use. It usually takes one of four forms:
Fee-linked gift:points, a voucher or cashback after you pay the joining fee
Spend-linked gift:a reward when you spend a set amount in a set number of days
Fee waiver:the joining fee is waived if you spend a set amount early, as on Axis ACE (₹10,000 in 45 days)
Bundle:a free subscription, a lounge pass or a hotel voucher
These are different things. A fee-linked gift only partly gives back what you paid. A spend-linked gift is free money, but only if the spend is real. A fee waiver is the only kind that removes the cost altogether. For how waivers work after year one, readHow Credit Card Fee Waivers WorkandAnnual Fee vs Joining Fee.
How Do You Work Out If a Welcome Benefit Is Worth It?
Use four steps. Convert the benefit to rupees, subtract the fee, count the spend you would not have made, and check the strings attached.
Step | Question | Example |
|---|---|---|
1. Value | What is the benefit worth in ₹? | 500 CashPoints × ₹0.15 = ₹75 |
2. Net of fee | Value minus the fee and taxes you pay | ₹75 - ₹500 = -₹425 |
3. Extra spend | Would you spend this amount anyway? | ₹10,000 in 90 days is easy if rent is not counted |
4. Strings | Where and when can you use it? | NeuCoins work only at Tata brands; vouchers expire |
Step 1 is where most people go wrong. A point is not a rupee. Amex does not state a cash value for its points, but its Gold Collection table implies about ₹0.33 for Amazon and Flipkart vouchers and about ₹0.58 for a Taj voucher, so 4,000 points could be worth ₹1,320 or ₹2,320. HDFC Freedom's CashPoint is ₹0.15 as cashback. Seehow to calculate the real value of 1 reward pointfor the method.
Step 3 is the one that costs real money. If you spend ₹10,000 more than you planned to reach a ₹500 benefit, you have not saved anything. The benefit is worth it only when the spend was already in your plan, for example a month of groceries and bills.
Which Welcome Benefits Are Worth Chasing?
Rank them in this order.
1. Lifetime-free cards with a spend-linked gift
There is no fee to recover, so every rupee is gain. IDFC FIRST Millennia's ₹500 voucher on ₹5,000 spend in 30 days is the clean example. You still need to read the voucher terms, as vouchers have brands and expiry dates.
2. A fee waiver you can earn on early spend
If a card waives the joining fee on ₹10,000 spent in 45 days, as Axis lists for ACE, the benefit is the whole fee, ₹499. That is bigger than most points gifts, and it needs only normal spend.
3. A gift that roughly equals the fee
SimplyCLICK's ₹500 gift card against a ₹499 plus GST fee comes to about even, but only if you use Amazon. Tata Neu Plus reverses its first-year fee in NeuCoins, which you can spend only at Tata brands. In both cases the first year is nearly free, and the second year is where the real fee shows up.
4. A gift much smaller than the fee
Freedom (₹75 against ₹500) and Flipkart Axis (₹250 against ₹500) do not cover their fees. These cards need to earn their place through everyday rewards, not the welcome gift. Seethe annual fee breakeven guide.
5. Large points gifts on premium cards
Amex Gold gives 4,000 points, which is bigger than the ₹1,000 first-year fee at either value in our maths. But the fee jumps to ₹4,500 plus taxes from year two, and the card is a charge card you must pay in full. A big first-year gift can hide a steep second-year fee.
What Should a First-Time Card Holder Check?
Freshers and beginners have thin or no credit history, so approval itself is the first hurdle. Do not apply to several cards for their welcome gifts: each application is a hard enquiry, which can lower your score for a time. Readhard vs soft enquiryandcredit card mistakes beginners should avoidfirst.
Under RBI'sCredit Cards and Debit Cards: Issuance and Conduct Directions, 2025 (updated as on 1 October 2026), card-issuers must give you the Most Important Terms and Conditions at onboarding, and the MITC must cover joining fees. The Directions also require reward benefits to be provided transparently, with details on the issuer's website and a copy for the cardholder. Unsolicited cards and upgrades are prohibited. So ask for the written terms for the welcome gift before you pay the fee.
One more point: terms change. The Directions require 30 days' notice of changes, but a welcome offer on the website today may not be the one on the card when you apply. Take a screenshot of the offer page and check the MITC.
A Worked Example
Take a fresher with a ₹40,000 monthly salary who plans to spend ₹15,000 a month on groceries, bills and transport. Two cards offer welcome gifts:
Item | Card A (₹500 fee, ₹250 voucher) | Card B (lifetime free, ₹500 voucher on ₹5,000 in 30 days) |
|---|---|---|
Planned spend in first 30 days | ₹15,000 | ₹15,000 |
Condition met by planned spend? | Not needed; fee-linked | Yes: ₹5,000 required, ₹15,000 planned |
Fee paid | ₹500 + taxes (about ₹590 at 18% GST) | ₹0 |
Welcome value | ₹250 | ₹500 |
Net first-month gain | -₹340 | +₹500 |
Card B wins the welcome round by about ₹840 without any extra spend. That says nothing about their everyday rewards, so compare those too, using thecredit card comparison guide. The 18% GST figure is our assumption; check your fee on the MITC.
Checklist
Convert the welcome gift into rupees using the issuer's own value per point
Subtract the joining fee and taxes
Check the spend needed, the time window and what is excluded from it
Note where the gift can be used and when it expires
Ask for the MITC and reward terms before paying the fee
Check the fee from year two, not just year one
Apply to one card at a time to protect your credit score
Common Mistakes to Avoid
Spending extra to reach a welcome target
Assuming a point equals a rupee
Ignoring the year-two fee
Missing the 30, 45 or 90-day window
Letting a voucher expire unused
Applying for several cards for gifts and triggering hard enquiries
Treating a welcome gift as a reason to keep a card you do not use
Related on benchmarksutra
FAQs
Are credit card welcome benefits worth it?
Only if the gift is worth more than the fee you pay and you would have made the spend anyway. In the cards we checked, many gifts were smaller than the fee.
What is a credit card welcome benefit?
It is a reward for joining or using the card early, such as points, a voucher, cashback or a joining fee waiver. Terms vary by card.
Do I have to pay the fee to get the welcome gift?
On several cards, yes. Freedom, Flipkart Axis, SimplyCLICK, Tata Neu and Amex Gold link the gift to paying the fee. Lifetime-free cards link it to spend.
Are welcome points worth a rupee each?
Not always. HDFC Freedom's CashPoint is ₹0.15 as cashback, while NeuCoins are ₹1 at Tata brands only. Amex states no cash value.
Can a bank change the welcome offer after I apply?
Terms can change, and RBI's Directions require 30 days' notice of changes. Keep the offer page and the MITC from the day you apply.
Should a first-time card holder chase welcome benefits?
No. Choose the card for its fee, everyday rewards and eligibility, and treat the gift as a bonus. Do not overspend or apply to many cards at once.
Do welcome benefits need a minimum spend?
Some do. IDFC FIRST Millennia needs ₹5,000 in 30 days, Amex Gold needs ₹10,000 in 90 days, and Axis ACE waives its fee on ₹10,000 in 45 days.
Official Sources and Editorial Note
Data checked as of: November 2026
HDFC Bank: Freedom credit card
https://www.hdfc.bank.in/credit-cards/freedom-credit-card
HDFC Bank: Tata Neu Infinity
https://www.hdfc.bank.in/credit-cards/tata-neu-infinity-hdfc-bank-credit-card
HDFC Bank: Tata Neu Plus
https://www.hdfc.bank.in/credit-cards/tata-neu-plus-hdfc-bank-credit-card
Axis Bank: Flipkart Axis Bank credit card
https://www.axis.bank.in/cards/credit-card/flipkart-axisbank-credit-card
Axis Bank: ACE credit card
https://www.axis.bank.in/cards/credit-card/axis-bank-ace-credit-card
SBI Card: SimplyCLICK
https://www.sbicard.com/en/personal/credit-cards/shopping/simplyclick-sbi-card.page
IDFC FIRST Bank: FIRST Millennia
https://www.idfcfirst.bank.in/credit-card/millennia
American Express India: Gold Card
https://www.americanexpress.com/in/charge-cards/gold-card/
Credit Cards and Debit Cards: Issuance and Conduct Directions, 2025 (updated as on 1 October 2026)
https://www.rbi.org.in/Scripts/NotificationUser.aspx?Id=13155&Mode=0
This article is written from official sources and does not rely on third-party wording. Rupee values are our calculation from the issuers' stated values; GST at 18% is our assumption. Offers change, so confirm current terms with the issuer before applying.